Thomas Laffont: The $4T AI IPO Wave Is Coming… and We’ve Never Seen Anything Like It · 苏菲拉底
字幕 字幕位置
--:--
点击播放,这里会跟随视频显示当前句的中英字幕。

Thomas Laffont: The $4T AI IPO Wave Is Coming… and We’ve Never Seen Anything Like It

节目发布 2026-06-04 · All-In Podcast
托托马斯·拉丰 查马斯·帕里哈皮蒂亚 JJason Calacanis / David Sacks
EDITED TRANSCRIPT · 依据现场录音编译整理,可划线生成便签
编者按:本文是 Coatue 联合创始人兼总裁托马斯·拉丰在 All-In 峰会上的主题演讲与对谈实录,这也是他首次登上播客节目。拉丰先以一组数据幻灯片梳理了独角兽经济的复苏、AI 巨头的增长曲线、SpaceX 的估值逻辑与 AI 收入的来源,随后与四位主持人查马斯·帕里哈皮蒂亚、杰森·卡拉卡尼斯、大卫·萨克斯和大卫·弗里德伯格就幂律、估值、公开市场的检验以及数万亿美元回流硅谷的后果展开讨论。本文依据现场录音编译整理。

播客首秀

拉丰: 你们猜我为什么把播客首秀留给 All-In?那些小角色都打过电话来,我说不,我就等着,等到几位好兄弟来叫我。

拉丰: Coatue 做的是想法的生意。当你手里握着一个真正革命性的想法,它可以变得非常大。我们当初决定进入这一行,就是为了找到伟大的创业者,找到伟大的公司。

拉丰: 今天我想做点不一样的事。几位已经连讲了好几个小时,现在可以歇几分钟,靠在椅背上。我会放一些幻灯片,带大家看一遍独角兽经济(unicorn economy)的最新状况。

独角兽经济回暖

拉丰: 市场回来了。自 2024 年 9 月以来,独角兽经济的平均估值上涨了 70%。我想这一点在座大多数人都有直觉。但更令人惊讶的是,公开市场几乎做出了同样幅度的上涨。如果看独角兽经济总值占纳斯达克的比重,这个数字从 2015 年起大幅攀升,过去几年却基本走平。我认为这说明了 Palo Alto 等上市公司的表现有多强。

拉丰: AI 正在主导融资。这张图有意思的地方在于,AI 的占比还在持续上升,已经连续多年在融资盘子里抢下更大的份额。但融资的构成变了。独角兽工厂(unicorn factory)的产量在 2021 年零利率时代(ZIRP)见顶,如今已回落到远低于疫情前的水平。把两者放在一起算一下,你会发现每家独角兽的平均融资额比 2021 年增长了五倍。也就是说,独角兽更少了,但每一家募的钱更多了。

三代队列的存活率

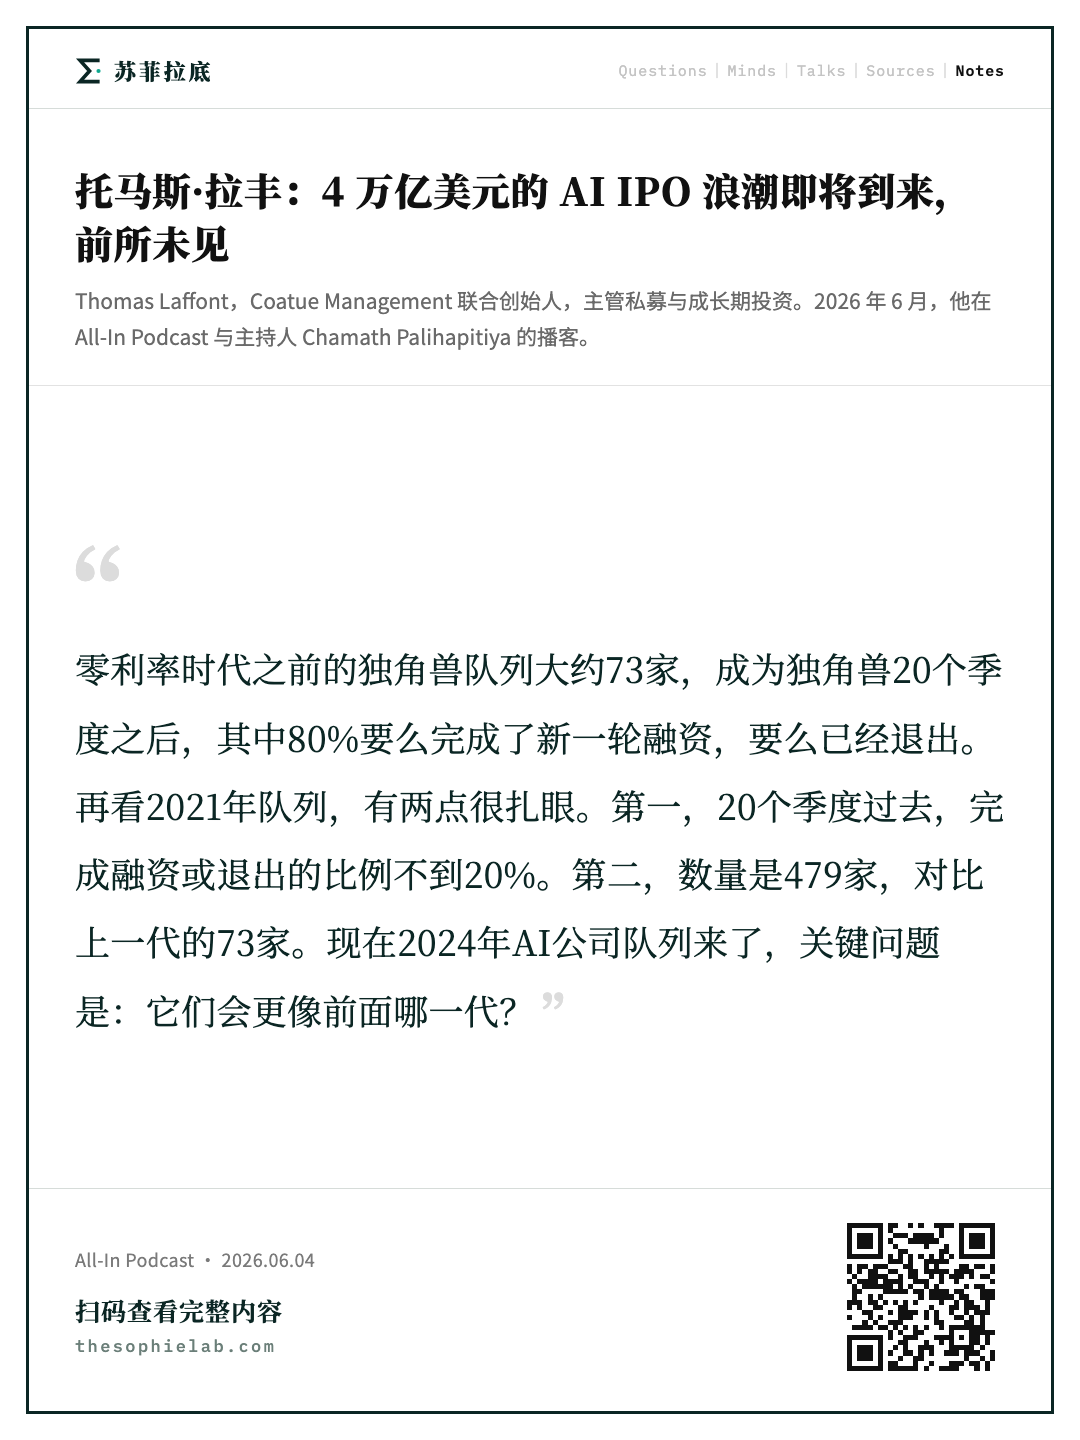
拉丰: 我要在这张图上多花一分钟,因为它关乎我们这个生态系统的健康。看绿线,这是零利率时代之前的独角兽队列,大约 73 家。成为独角兽 20 个季度之后,其中 80% 要么完成了新一轮融资,要么已经退出。我认为这相当健康。

拉丰: 再看 2021 年队列,也就是红线,有两点很扎眼。第一,20 个季度过去,完成融资或退出的比例不到 20%。第二,看看数量,479 家,对比上一代的 73 家。现在新一代来了,我们称之为 2024 年 AI 公司队列。关键问题是:它们未来会怎样?会更像前面哪一代?

新「壮丽八巨头」

拉丰: 前面说到 AI 正在把独角兽的融资盘子集中起来,但我们还看到,前十名公司拿走了相当大一块融资。所以不只是 AI 公司在吸金,而是极少数几家 AI 公司在吸金。这也合理,我们都知道 Anthropic 和 OpenAI 在募巨额轮次。

拉丰: 由此我想到,我们其实有了一个新指数。如果认真想想未来的指数长什么样,眼下我暂且叫它「壮丽八巨头」(Magnificent Eight),当然随着这些公司陆续上市,这个数字还会缩小。我第一反应是:好一群了不起的公司。再看它们的多样性:SpaceX、Stripe、Anthropic、Databricks、Revolut、字节跳动、Anduril。有互联网,有 AI,有金融科技,有太空科技。如果能买,我很乐意在接下来十年以上一直持有这个指数。

拉丰: 这个指数的表现自然也是惊人的。它代表将近 4 万亿美元的价值,彻底碾压了传统的「壮丽七巨头」(Mag 7)。其中几乎每一家的表现都超过了那个指数。

退出解冻

拉丰: 另一个积极信号是退出正在解冻。这些年我和几位主持人反复讨论一件事:我们知道独角兽经济很擅长消耗现金,但它究竟回吐了多少现金?消耗的现金和返还的现金必须有一个平衡,生态系统才能维持。看数据,2026 年的趋势相当不错,虽然还没回到 2021 年的水平,但已经很可观,而且今年还剩半年。

拉丰: 这还不包括我们知道很快要上市的三家公司。SpaceX 显然就在几周之内。Anthropic 今天刚刚传出消息,已经秘密递交了 S-1。光把这三家加起来,就基本超过了过去十年的总和。这意味着什么?如果你 2024 年在第一届 All-In 峰会现场听过我的演讲,就会记得当时我们的生态系统是失衡的:消耗的现金远远多于返还的现金,这是根本性的失衡。而现在,即便还没算上我刚才提到的那几场流动性事件,我们的生态系统也已经平衡得多了。这一点还会继续改善。

超速增长曲线

拉丰: 部分原因是 OpenAI 和 Anthropic 的增速前所未见。看这张图,请记住它的起点是 2025 年 1 月,距今只有一年半。才几个月,这两家公司的收入就超过了 Workday,一家相当了不起的人力资源软件公司。然后是 ServiceNow。年底超过了 Adobe。今年 1 月又超过了 Salesforce。现在甚至比 Google Cloud 和 Azure 还大。

拉丰: 未来会怎样?这只是基于一些假设和预测,但我们的估计是,它们不仅已经比 Azure 大,到今年年底可能超过 AWS,到 2028 年有可能超过整个微软。

拉丰: 这些超大规模云厂商(hyperscalers)并没有坐以待毙。他们看到了颠覆,而且不只是看到,他们在出钱资助这场颠覆。看看 ChatGPT 时刻之后,这些全世界最大的公司为推动和创造这场变革投入了多少。真正史无前例。

SpaceX 估值框架

拉丰: 我知道很多人要谈 SpaceX,所以我想分享一下我们作为投资人是怎么看 SpaceX 的。无论你是在考虑要不要持有这只股票,还是只想在鸡尾酒会上显得更聪明,都可以借用我们的功课。

拉丰: 研究 SpaceX,第一个跳出来的结论是:与它估值相关性最高的驱动因素是发射频次。这在直觉上说得通,你做的是发射生意,发射得越多,价值就应该越高。数据里确实能看到这一点。但我想指出另一个本质上不同的比率:如果拿估值除以发射次数,会是什么样?

拉丰: 你会看到它在一段时间里一直处于固定区间,然后开始明显上行。我们相信市场是理性的,所以我们开始思考:为什么 SpaceX 在发射次数更多的时候,市场反而给它每次发射更高的估值,而不是在起步阶段?我的根本看法,姑且称之为 Coatue 框架,是 SpaceX 商业模式的质量随发射次数而提升。

拉丰: 第一阶段,我们叫「星座前」(pre-constellation),你还在试自己的火箭,而火箭是很难的。也许有几个政府客户,但那是一次性收入,不可预测。然后进入初步爬坡期,你可能有了一个星座。为什么星座重要?因为它是一个终端市场,而且是经常性收入的生意。卫星放得越多,订户越多,收入越多。接着你从爬坡进入规模化,不再只有一个星座,而是多个星座。我们认为最终会有各种各样的公司、政府和军队想拥有自己的星座,以便掌握自己的命运。到这一步你就成了规模化的业务,并最终成为一个平台。我们都知道在这个技术时代平台有多值钱。平台意味着不仅核心业务的客户多得多,还会长出新业务:可以是太空数据中心,可以是月球、火星和其他太空应用的期权价值。

越大反而越容易

拉丰: 这个时代的标志性特征是这些公司扩张的速度。无论对比个人电脑、互联网还是移动时代,Anthropic 的扩张速度都是我们前所未见的。

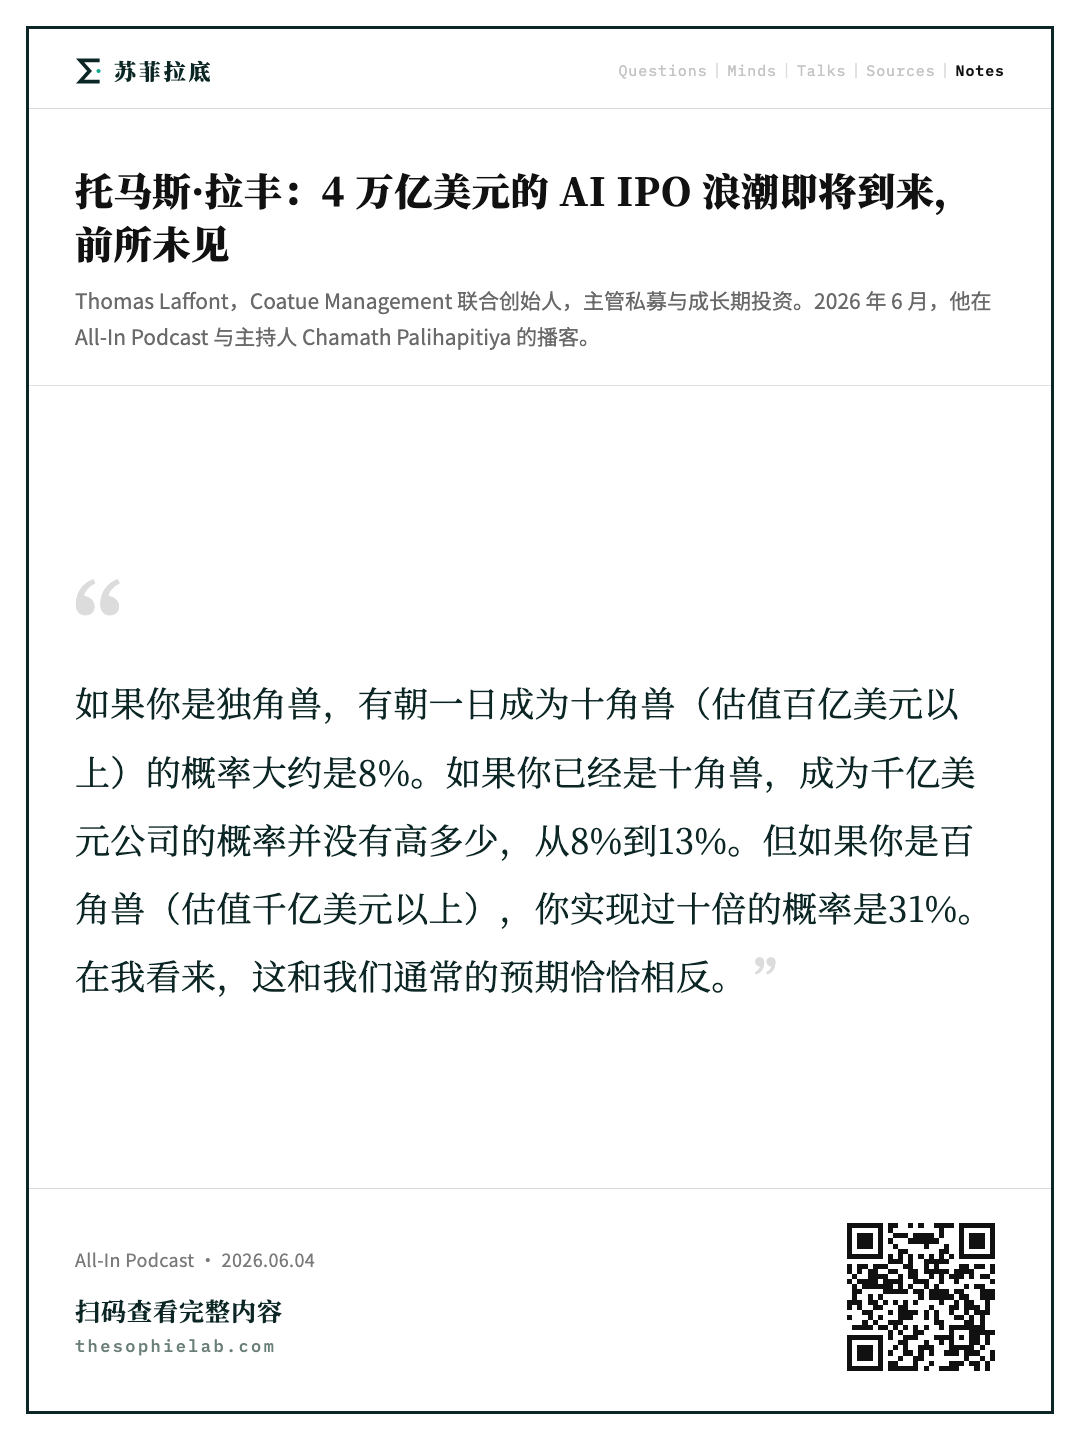
拉丰: 接下来这个分析很有意思,我也很想和几位讨论。我们把公司分成三组,然后问:在每一组里,出现十倍回报的概率有多大?在我这样的投资人看来,也许不算杰森那样的种子投资人,但对我们成长期投资人来说,十倍已经非常好了,很难找。数据告诉我们:如果你是独角兽,有朝一日成为十角兽(decacorn,估值百亿美元以上)的概率大约是 8%。如果你已经是十角兽,那么成为千亿美元公司的概率并没有高多少,从 8% 到 13%。但有趣的是,如果你是百角兽(centacorn,估值千亿美元以上),顺便说一句,这里我们把上市公司和非上市公司都算进去了,那么你实现过十倍的概率是 31%。在我看来,这和我们通常的预期恰恰相反。

拉丰: 再看这些公司创造价值的速度。这张图是我最后一刻加进来的,因为数据实在太新鲜。通常从 5000 亿美元市值涨到 1 万亿要花好几年。但最近公开市场发生了一件事:不仅有三家公司在同一年完成了这一跨越,而且其中两家是在几周之内完成的。这能得出什么结论,我们等会儿可以聊。

Cerebras 与半导体行情

拉丰: 就在这些公司以惊人速度从 5000 亿冲向 1 万亿的同时,也有公司花了很长时间才走到成功。Cerebras 刚刚上市,是个很好的例子。我长期担任它的董事,并领投了 B 轮,对此非常自豪。但看看这家公司的融资史,你就明白我为什么在图上放了一个施工的小图标:它熬了很久,有过一些黑暗时期,好几年没有新资本进来,全靠苦干去打磨技术。这一切最后换来了一份巨大的 OpenAI 合同,公司估值随即翻了五倍。

拉丰: Cerebras 成功了,而且坦白说不止 Cerebras。半导体正处于一轮世代级的大行情。我早些时候还在和朋友布拉德·格斯特纳(Brad Gerstner)聊这件事。仅从 2024 年 All-In 峰会算起,你就能看到半导体行业跑赢指数多少。

记忆需求与内存股

拉丰: 未来会怎样?今天上午听了这么多演讲者,我的一个收获是,大家似乎普遍同意:AI 系统对你的业务、对你这个用户了解得越多,就越有用。你去订餐厅的时候,希望它已经知道你的偏好,几点吃饭,爱吃什么,等等。所以我们认为,在这个时代,仅仅因为 AI 系统为了提供服务而产生的需求,每个用户对应的内存用量就可能增长五倍。这有助于解释为什么我们看到内存公司的股价出现了那样的走势。

AI 收入三大支柱

拉丰: 最后我想谈一个争议很大的问题:收入在哪里?回想过去 12 到 24 个月,大家一直在讨论:有没有收入?有没有投资回报?这些钱究竟对应着什么?所以我们试着去看:AI 生态系统究竟有多大?我们认为今天大约是 1400 亿美元,今年会到 3000 亿左右,2027 年再翻一倍。那么这些收入从哪里来?

拉丰: 拆开来看,我们估计这个行业有三根关键支柱。第一根大家都知道,消费者。订户数乘以每用户平均收入(ARPU),就是消费端的收入。第二根我想很多人忘了,是广告。我们估计目前 Meta 和 Google 投放的广告里,大约四分之一是 AI 驱动的。我们认为这个渗透率最终会到 100%,那是 1500 亿美元。第三根显然是企业端的突破,大家都知道 Claude Code 和 Codex 正在企业内部做什么。把这三块加起来,你就能对这个生态系统的规模有一个清楚的认识。

全行业颠覆

拉丰: 这是我倒数第二张幻灯片。在我看来,这个时代和我此前作为投资人经历过的时代有一点不同:此刻几乎每一个经济部门都在被改造。一些显而易见的领域我们都清楚,比如软件。但看看电信。我相信几年之内,Starlink 会驱动一种设备,让你真的可以在世界任何地方打电话。我们认为这在技术上已经解决了,而每一次通话掉线都在提醒我们,外面有更好的技术。回到尼克什(Nikesh Arora)讲的利润池(profit pool)框架,我认为 Starlink 的利润池,就是全球电信业宽带加无线的利润池。

拉丰: 我们知道算力正在推动半导体的巨变。早些时候有参议员告诉我们,数据中心如何改变了宾夕法尼亚州的能源格局。再想想汽车业。我相信很多人关注了上周法拉利的事,它试图推出电动和自动驾驶的新技术,这引出一个问题:在一个自动驾驶和电动化的世界里,这个品牌的未来是什么?我认为市场对那辆车的反应恰好印证了这种叙事。然后显然是消费领域,我们知道 GLP-1 类药物正在深刻影响食品和酒精的消费、饮食结构,以及对健康的高度关注。

拉丰: 把这些放在一起,结论是什么?第一,新的独角兽经济更健康了,这真要感谢 AI。第二,赢家的复利速度前所未有,这意味着不在赢家里的代价也前所未有地高。第三,颠覆正在波及全球经济的每一个角落。顺便说一句,我们甚至还没有超级智能。距离我上次参加 All-In 峰会大约两年了,我开始想:两年后这一切会是什么样?我们知道那将是极为有趣的时期,也很庆幸有这么一群人帮我们看清接下来两年的路。

幂律之下如何配置

卡拉卡尼斯: 我们给这场谈话起个标题:幂律统治我们的生活。所有巨大的收益都在向极少数公司集中,而这些公司依然强劲。你怎么看私募市场生态的演变,也就是场上这盘棋,因为公司留在私募阶段的时间更长了,又出现了这些超乎寻常的结果?我显然在最早期运作。有人做 A 轮,比如 Craft Ventures。你们这样的机构则向下延伸进入私募。我刚和布拉德·格斯特纳聊过,你们前面也提到他,他说:我得想清楚把时间放在哪里。他们既做早期,也和你们一样做公开市场。再加上像安德森·霍洛维茨(Andreessen Horowitz)这样的机构,可能在大举追求平均回报,把风险投资指数化。对于有限合伙人(LP)、天使投资人和风投机构来说,未来十年、二十年的赛场会是什么样?这一切要怎么梳理成一套连贯的策略?因为私募市场的运作方式显然已经和二十年前的剧本大不相同。

拉丰: 我想第一层拆解,从账本的正面看,结果变大了。我们在私营公司里看到了过去想都不敢想的结果。我认为这对整个生态系统总体上是好事。这正是我想放那张 SpaceX 幻灯片的原因,发射生意这一点对我来说有些反直觉:为什么一家公司发射得越多,估值反而越高?所以至少我们有了一批大结果。而这些结果似乎会在 12 个月之内进入公开市场。回想零利率时代,结果更小,公司也不上市。至少在这个时代,我们有大结果,这些公司也有上市的意愿。Anthropic 和 OpenAI 都公开表示想上市。我认为这是好的。

拉丰: 最大的问题在于,我们似乎在生活的每个方面都在谈 K 型分化和幂律,而初创企业似乎也是如此。看我那张百角兽的图,我们在那个数字上已经卡了一阵子了。杰森,我想你问的要点是:如果未来十年没有新的百角兽出现,事实上过去几年我们几乎没有看到新的,那对我们来说就是一个警示信号。

卡拉卡尼斯: 这对资本配置者意味着什么?按你展示的东西,一个理性的 LP 会说:等谁涨到千亿美元,然后把手里每一块钱都梭哈进去,因为那是最确定的,最不脆弱的,最省力的,回报也最快。但我们都知道,供需决定估值。这些估值正在脱离我们见过的任何估值指标。今天比尔·阿克曼(Bill Ackman)给我们讲得很准确:你是在对万亿美元公司做风险投资,给它们 50 倍、100 倍营收的估值。所以请谈谈,作为有限合伙人、私募投资人、高净值和超高净值个人,理性地讲,钱应该往哪里放?所有人都抢着挤进三个名字,你担心吗?

拉丰: 显然,过去五年那就是正确的策略。问题在于接下来的五年。

卡拉卡尼斯: 对。

拉丰: 关于估值这个论点,我唯一想反驳的是:这些不是假公司。

卡拉卡尼斯: 绝对不是。

拉丰: 我记得 2000 年的泡沫,也记得 2021 年。而这些公司在大规模地产生可观收入,增速比我们见过的任何东西都快。这些生意是真实的,而且业绩在兑现。据广泛报道,Anthropic 甚至有过一个盈利的月份,所以它们也算得上盈利了。

公开市场是试金石

拉丰: 但归根结底,查马斯,我想你也同意,公开市场是最终的检验。

查马斯: 均衡器。

拉丰: 对,是规模的检验。它会是最好的消毒剂。它不在乎我的演示,不在乎任何人怎么说。我喜欢这一点。我喜欢这些公司,SpaceX、OpenAI、Anthropic,都必须直面市场的审视。我是市场的坚定信徒,所以我非常期待看到这些公司上市,去经受卖空者、评论家、辩论者和政客的检验。

查马斯: 我问你两个问题。第一个很战术性。通常我们会说,消毒或者说杀菌在上市第一天就发生了。

拉丰: 对。

查马斯: 但现在规则变了,会有大量被动买盘,所以这个日期会往后推,因为得先把供需消化一遍。所以可能要到……

拉丰: 六个月加一天。

查马斯: 六个月加一天,也就是锁定期结束之后,我们才能真正开始看清这些公司是什么。好,这是战术问题。更具战略性的问题是,托马斯,你认为是不是存在某种结构性的低效或者错误,让这些复利机器能在如此规模上继续加速?这是市场效率的问题,还是幸存者偏差,我们不该过度解读?你怎么看?

拉丰: 我不想过度解读,因为样本太小了。看 Anthropic,Claude Code 之前的 Anthropic 和 Claude Code 之后的 Anthropic 是两家完全不同的公司。一个事件就彻底改变了几乎整个行业的轨迹。所以我很难判断这是否真的……这些公司会不会像《基地》系列里的「骡」(the Mule),一个完全无法预测、凭空出现的一次性事件。我们走着瞧。但我确实认为,「这些模型是大宗商品,这些公司会被商品化」这种叙事,现在已经被相当彻底地证伪了。

扩张中的投资定力

查马斯: 你们的资产规模膨胀了,策略也扩展了,现在还在做数据中心,做很多事情。你怎么把这一切理顺?也许这样一张幻灯片会让你说:等一下,我们是不是干脆把 100 亿美元砸进美光(Micron)就好了?你怎么平衡?

拉丰: 这正是我做这样一份材料的原因。某种意义上我该感谢你们,因为为你们做这件事要耗费我和团队大量时间,我们真心想呈现准确的信息。过去两周基本是全职在做这件事。但对我而言,它重新锚定了我的信念,让我知道该做什么。我不可能去听一千个人的话,那样我会分心,会不知道自己在想什么。回到数字和估值这些基本事实,能把我带回一个有信念的位置。所以每当我试图理解这个世界,我都会回到:我懂什么?我懂模型,我懂数字。让我回头把这些东西剥开来看。我希望这份材料能说明的是:现象背后有实实在在的原因。看看那些几周之内成为万亿美元公司的企业,它们不是假公司。这些公司已经存在几十年了,而且它们的市盈率几乎是标普 500 里最低的。所以确实有某种真实的东西在发生。

查马斯: 有一股能量刚刚被释放出来。

拉丰: 对。然后有人跟我提了一个关于内存的观点,你会喜欢的。他说,如果我想像 OpenAI 那样设计一颗芯片,我可以去找台积电。我知道这很难,但至少有台积电帮我。而如果我想做内存,没有台积电这样的选项。那么内存公司的估值倍数,相对于专用芯片(ASIC)公司,应该是多少?

万亿之后还能十倍吗

卡拉卡尼斯: 莉娜·汗(Lina Khan)的怒火在这里面看得很清楚。萨克斯,我想听你谈谈政策和选举对这些结果有多大影响。

萨克斯: 我看到的,不知道是不是这张图,是你展示每一类公司跃升到下一级的概率的那张。

拉丰: 好奇问一句,你事先会这么预测吗?

萨克斯: 非常反直觉。我的思路是再往外推一步:万亿美元市值的公司涨到 10 万亿的概率是多少?上一级是 31%。在我看来会是 50%?100%?我不知道。我在想的是,会大于还是小于 30%?在我看来,超过 30% 的公司会做到。

弗里德伯格: 这大概是一种筛选机制,筛的是这家公司的复利优势和盈利的持久性。每上一个台阶都有一道筛子在问:你有复利优势吗?你的盈利持久性更强了吗?如果是,你就会加速进入下一阶段。这几乎就是最基本的企业估值分析,本杰明·格雷厄姆式的分析。

萨克斯: 要进入所谓的万亿美元俱乐部,你必须有一门占据主导地位的生意。然后问题只是,你在哪一点上触及饱和?而看起来所有这些市场最后都比任何人预测的大得多。

弗里德伯格: 还有垄断,或者政府干预。从根本上说,想想贝尔系统(Bell System)的拆分,谁知道它后来会走到哪里。它本可以垄断互联网,本可以垄断商业,垄断电子商务,以此类推。

查马斯: 但作为一种交易策略,你想要的是一个机器人,一家公司一旦触及 1 万亿,它就开始买进这家公司的股票。

卡拉卡尼斯: 而且如果你真这么做了,很多……我记得第一家触及 1 万亿的公司是谁?是苹果吗?

拉丰: 我想是的。

卡拉卡尼斯: 对,当时所有人都说:天哪。而现在有多少家了,五家?

弗里德伯格: 抱歉打断一下,有一项研究显示,如果你买纳斯达克,持有十年,可以得到大约三倍或者相当可观的回报。而如果你只买纳斯达克市值前十的公司,每年按市值前十重新平衡一次,十年下来能跑赢大约三倍。

数万亿回流之后

查马斯: 托马斯,你为什么不那么做?也许问最后一个问题,好让我们按时收尾,这件事我认为你的位置最适合回答。当所有这些钱分配回来的时候会发生什么?你觉得你们的竞争格局会怎样?创业者的格局会怎样?当三四万亿美元回到普通合伙人(GP)手里,再回到 LP 手里,然后开始循环再投资,硅谷会发生什么?

拉丰: 我首先想到的是,我记得大卫当年对加州房地产多么看空。我们看看这波资本涌入会不会……

萨克斯: 该卖了。

卡拉卡尼斯: 旧金山的房子还是……

查马斯: 对,不如把那座陵墓买下来。

萨克斯: 有人对一座四万平方英尺的陵墓感兴趣吗?

卡拉卡尼斯: 抗议者不包含在内。

拉丰: 关于 SpaceX,我想说一点。我不知道 1.75 万亿美元是不是 IPO 的合理价格,坦白说我毫无头绪。我知道的是,全球电信和服务提供商的利润池在 2000 亿到 4000 亿美元之间,取决于你想覆盖哪些部分。所以你必须想一想,这家公司光靠核心业务,而且这项业务几年前甚至还不存在,就在用一个明显更好的产品去攻一个数千亿美元的利润池。我们所有人一想到 Starlink,都知道它随时都能用,不需要无线电塔。

拉丰: 所以回到你的问题,查马斯,很难知道,因为我们从未经历过这样的事。终极问题也许是:回看网约车大战和外卖大战,到某个节点,过剩的资本被用来打价格战。

查马斯: 对。

拉丰: 那么 OpenAI 和 Anthropic 之间会不会爆发价格战?如果这些公司手握如此多的资本,其中一家会不会有一天拉动价格杠杆来对付另一家?

查马斯: 理性地讲,它们应该这么做。

拉丰: 应该。所以我们可能会看到今天无法预测的事情,比如有公司说:我手里有 2000 亿美元现金。当然问题在于它们在基础设施上的花费也太大了,所以答案并不显而易见。但我确实认为我们会看到一些反直觉的变化。你们每周都会在节目里讨论这些。希望两年后我能回来,分析一下哪些判断对了,哪些错了。

每年回归复盘

卡拉卡尼斯: 说真的,我认为你应该每年都回来,让我们都受益。

查马斯: 对,定下来。

拉丰: 定下来。

卡拉卡尼斯: 我们付钱,付这两周的工作。我们真的很感激。

查马斯: 真心感谢你的付出和努力,我知道这很不容易。你把这些带给观众,太好了。这也说明有时候慢下来,认真思考现实的真实状态,有多大的力量。这让人脚踏实地。

卡拉卡尼斯: 从你嘴里说出「脚踏实地」,真是意味深长。

查马斯: 我分不清这是恭维还是讽刺。

拉丰: 我就说一句谢谢。

卡拉卡尼斯: 谢谢查马斯这句了不起的恭维,也谢谢托马斯的到来。谢谢。
本期讲者
托马斯·拉丰Coatue Management 联合创始人,主管私募与成长期投资。Coatue 是 1999 年成立的老虎系对冲基金,管理规模约 550 亿美元,投资过 Anthropic、Databricks、Cerebras 等公司。
查马斯·帕里哈皮蒂亚Social Capital 创始人、All-In 播客联合主持人,曾任 Facebook 增长副总裁。以宏观与市场结构判断著称。
Jason Calacanis / David SacksJason Calacanis 是早期天使投资人(Uber、Robinhood 早期投资者),All-In 主持人;David Sacks 是 Craft Ventures 创始人、前 PayPal COO,2025 年起任白宫 AI 与加密事务负责人。
章节 · 点击跳转视频
0:00 片头:Coatue 与 All-In 的登场 ▶ 正在看
0:25 独角兽经济回暖与融资集中 ▶ 正在看
3:33 「壮丽八雄」与退出回暖 ▶ 正在看
6:11 OpenAI 与 Anthropic 的增速曲线 ▶ 正在看
8:05 SpaceX 估值框架:发射频次与平台化 ▶ 正在看
10:58 十倍概率悖论与 Cerebras 长跑 ▶ 正在看
13:45 内存需求、AI 收入三支柱与全行业颠覆 ▶ 正在看
18:32 圆桌:幂律之下资本该去哪 ▶ 正在看
22:11 公开市场是消毒剂:估值与审视 ▶ 正在看
27:18 万亿俱乐部的筛选机制与垄断天花板 ▶ 正在看
29:20 资本回流、SpaceX 定价与价格战 ▶ 正在看
31:53 收尾致谢 ▶ 正在看
本期论点
本期回应
其他论点
2:37
2021届独角兽在20个季度后不足20%完成新融资或退出,零利率时代前那批为80% 观察托马斯·拉丰
4:05
SpaceX、Stripe、Anthropic等私营巨头比美股七巨头更值得长期持有 托马斯·拉丰
5:34
SpaceX、Anthropic等三家即将上市公司的退出金额将超过过去十年退出总和 托马斯·拉丰
7:01
OpenAI与Anthropic年底收入有望超过AWS,2028年或超过整个微软 托马斯·拉丰
7:25
超大规模云厂商不只是旁观AI对自身的颠覆,还在用自己的钱资助它 托马斯·拉丰
9:05
SpaceX商业模式的质量随发射次数增加而提升,推高了单次发射对应的估值 托马斯·拉丰
11:23
独角兽十倍成长概率约8%,十角兽约13%,千亿美元级公司高达31% 观察托马斯·拉丰
14:21
AI时代单个用户所需的内存量最终可能翻五倍 托马斯·拉丰
15:38
Meta和谷歌约四分之一的广告投放由AI驱动,这一渗透率最终会达到100% 托马斯·拉丰
21:45
顶级私营公司估值脱离以往任何指标,等于用50到100倍收入给万亿级公司做风投 查马斯·帕里哈皮蒂亚
23:57
被动资金的大量买入会把IPO的价格发现推迟到锁定期结束后约六个月 查马斯·帕里哈皮蒂亚
25:01
「大模型会被商品化、模型公司只是大宗商品生意」的说法已被彻底证伪 托马斯·拉丰
29:12
每年重新平衡、只持有纳斯达克市值前十的公司,十年回报约为大盘的三倍 观察Jason Calacanis
30:17
全球电信和服务运营商的利润池总共只有约2000亿到4000亿美元,SpaceX正在切入 观察托马斯·拉丰
31:30
AI公司基础设施开销过大,价格战空间不如当年的网约车和外卖平台 托马斯·拉丰
01片头:Coatue 与 All-In 的登场
0:00
Why do you think I waited to make my world podcast premiere for all in? All the ankle biters called and I said, "No, I'm just going to wait. [laughter] I'm going to wait till the besties call." >> Coatue is one of the most successful hedge [music] funds of the last two decades. >> $55 billion under management. >> This is their flagship hedge fund. >> The reason we decided to kind of get into this business is to find great entrepreneurs and find great companies. >> And they're looking to raise a whole billion dollars more [music] to invest in AI.
你以为我为什么一直等到 All In 才做我的播客首秀?那些小角色都来找过我,我说:「不,我就等着。[笑声] 我要等到 besties 来找我。」>> Coatue 是过去二十年最成功的对冲[音乐]基金之一。>> 管理规模 550 亿美元。>> 这是他们的旗舰对冲基金。>> 我们决定进入这一行的原因,就是去找到伟大的创业者、找到伟大的公司。>> 而且他们还打算再募集整整十亿美元[音乐]来投 AI。
便签引用
02独角兽经济回暖与融资集中
0:25
>> We're in an idea business and when you have a truly revolutionary idea, it can get really big. >> I hope to do something a little bit different. Besties, you've been on for a couple hours, so you can take a break now for a few minutes. Sit back. We are going to show you some slides. And we're going to walk you through really an update on the unicorn economy. So, the markets are back. We can see that the unicorn economy on average since September of '24 is up 70%. I think that's intuitive to a lot of us.
>> 我们做的是创意的生意,当你有一个真正革命性的想法时,它能做得非常大。>> 我希望做点不太一样的东西。Besties,你们已经聊了好几个小时了,现在可以休息几分钟。往后靠一靠。我们要给你们看几张幻灯片。我们会带你们过一遍独角兽经济的最新情况。那么,市场回来了。我们可以看到,自 2024 年 9 月以来,独角兽经济平均上涨了 70%。我想这一点对我们很多人来说是符合直觉的。
便签引用
0:55
But, what's even more amazing is that the public market has really made the same move up. So, if we look at the share of the unicorn economy of the NASDAQ, which had a significant move up since 2015, it's really kind of plateaued over the past few years and I think it speaks to the performance of public companies like Palo Alto and others. So, AI is dominating fundraising. What's kind of interesting in this slide is you can see their share continues to increase. So, multiple years in a row now that AI is increasing its wallet share of fundraising.
但更让人惊讶的是,公开市场其实也走出了同样的涨幅。所以如果我们看独角兽经济占纳斯达克的比重,它从 2015 年起有过一次显著上升,但过去这几年基本上已经走平了,我认为这说明了 Palo Alto 这类上市公司的表现。那么,AI 正在主导融资。这张幻灯片有意思的地方在于,你可以看到它们的份额还在继续上升。所以现在已经连续好几年,AI 在融资中占的钱包份额都在增加。
便签引用
1:33
But, the composition of that funding has changed. If you look at the unicorn factory, which really peaked in the ZIRP era of 2021, we've now really normalized at a much lower level pre-COVID. So, mathematically, if you put both together, you can see that the funding per unicorn has increased 5x since 2021. So, we have fewer unicorns that are each raising more. Now, I'm going to spend a minute on this slide because this slide is really about the health of our ecosystem. So, the way you interpret this is if you look at the green line, which is the pre-ZIRP era unicorn cohort, of which there's about 73, you can see that 20 quarters after becoming a unicorn, 80% of them had either raised a new round or exited, which is, I would say, pretty healthy.
但这些资金的构成变了。如果你看「独角兽工厂」,它其实在 2021 年的零利率时代达到了顶峰,而我们现在已经回落到远低于疫情前的水平并稳定下来。所以从数学上讲,把两者放在一起看,你会发现自 2021 年以来,每家独角兽拿到的融资额增长了 5 倍。也就是说,独角兽数量更少了,但每一家募的钱更多了。现在我要在这张幻灯片上多花一分钟,因为这张幻灯片真正讲的是我们这个生态的健康状况。解读方式是这样的:如果你看那条绿线,也就是零利率时代之前的独角兽群体,大概有 73 家,你可以看到,在成为独角兽之后的 20 个季度里,其中 80% 要么完成了新一轮融资,要么已经退出,我会说,这相当健康。
便签引用
2:33
Now, if we look at the 2021 cohort, which is the red line, two things stand out. First, that 20 quarters in, you can see less than 20% less had either exited or raised. But, look at the number, 479 versus 73 in the prior cohort. So, now here comes this new cohort, what we'll call our 2024 cohort of AI companies, and the key question is, what will happen in the future? Which of these cohorts will they resemble the most? So, we talked about how AI is concentrating the funding base of unicorns, but what we also see is the top 10 is capturing a significant share of funding. So, it's not just AI companies, it's a small number of AI companies, which probably makes sense since we know that Anthropic and OpenAI are raising massive rounds.
那么,如果我们看 2021 年那一批,也就是红线,有两点很突出。第一,20 个季度过去了,你可以看到只有不到 20% 要么退出、要么完成了新一轮融资。但看看这个数字,479 家,而前一批只有 73 家。那么,现在新的一批公司来了,我们称之为 2024 届 AI 公司,关键问题是,未来会发生什么?它们最终会更像哪一届?我们刚才讲到 AI 正在让独角兽的融资越来越集中,但我们还看到,排名前十的公司拿走了相当大一部分融资。所以不只是 AI 公司拿走了钱,而是极少数几家 AI 公司拿走了钱,这大概也说得通,因为我们知道 Anthropic 和 OpenAI 都在融巨额的轮次。
便签引用
03「壮丽八雄」与退出回暖
3:33
And so, what I like to think is we kind of have a new index. If we really thought about what the index of the future is, what for now I'll be able to call the Magnificent Eight, but that number is going to shrink as these companies go public, the first thing that jumps to my mind is, "Wow, what an incredible group of companies." And look at the diversity. SpaceX, Stripe, Anthropic, Databricks, Revolut, ByteDance, Anduril. We have internet, we have AI, we have fintech, we have space tech. I'd feel pretty comfortable owning this index if I could for the next decade plus.
所以我倾向于认为,我们其实有了一个新的指数。如果我们真的去想,未来的指数会是什么样,我暂且称它为「壮丽八雄」(Magnificent Eight),但随着这些公司陆续上市,这个数字还会缩水。我脑子里冒出的第一个念头是:「哇,这组公司太厉害了。」上市,我脑子里第一个冒出来的念头就是:"哇,这群公司也太厉害了吧。"而且看看它的多样性。SpaceX、Stripe、Anthropic、Databricks、Revolut、字节跳动、Anduril。有互联网,有 AI,有金融科技,还有太空科技。如果可以的话,未来十年甚至更久,我会很安心地持有这个指数。
便签引用
4:11
And obviously the performance of this index has been incredible. It represents almost $4 trillion of value and has really crushed the traditional kind of Mac 7. Almost every single one of these names has outperformed that index. We'll go to the next slide. Now, another positive sign is that if we look at the exits, the exits are thawing. So, one of the things that we've talked a lot about with the besties over the years is we know the unicorn economy is great at consuming cash, but how much cash is it really returning?
显然这个指数的表现非常惊人。它代表了将近 4 万亿美元的价值,而且实实在在地碾压了传统的「美股七巨头」。这里面几乎每一个名字都跑赢了那个指数。我们看下一页。另一个积极信号是,如果我们看退出情况,退出正在回暖。这些年我和几位老友(besties)聊得很多的一点是,我们知道独角兽经济很擅长烧钱,但它到底返还了多少现金?
便签引用
4:53
We need to have a balance between the amount of cash consumed to the amount of cash returned. That's how an ecosystem stays in balance. And if we look, 2026 is actually on a pretty good trend. Not quite where 2021 was, but pretty good. And we still have half a year to go. But, that doesn't include three companies that we know will be coming public pretty shortly. SpaceX obviously in the next few weeks. And we know Anthropic just today the headlines hit that they've submitted confidentially for their S-1.
我们需要在烧掉的钱和返还的钱之间找到平衡。一个生态系统就是这样保持平衡的。我们来看,2026 年其实趋势相当不错。还没到 2021 年的水平,但已经相当好了。而且今年还有半年时间。但这还没算上我们已经知道很快就要上市的三家公司。SpaceX 显然就在未来几周。而且我们知道,Anthropic 就在今天有消息称,他们已经秘密提交了 S-1。
便签引用
5:34
And if you add up the totality of just those three companies, you can see that it's basically going to be more than the 10 years kind of combined. Which ultimately means, if you remember and you were there when I presented the first all-in summit in 2024, we knew our ecosystem was out of balance. We were consuming way more cash than we were returning. Which is just a fundamental imbalance and you can see that now even pre-the liquidity events that I just mentioned, our ecosystem is significantly more balanced.
如果把这三家公司加总起来,你会看到,它基本上会超过过去十年的总和。这最终意味着——如果你还记得,你当时也在场,我在 2024 年第一届 All-In 峰会上讲过——我们知道我们的生态系统失衡了。我们烧掉的钱远远多于返还的钱。这是一个根本性的失衡,而现在你可以看到,即便在我刚才提到的那些流动性事件发生之前,我们的生态系统已经平衡得多了。
便签引用
04OpenAI 与 Anthropic 的增速曲线
6:11
And that will continue to improve. Part of it is that the growth rates of OpenAI and Anthropic are unlike anything that we've ever seen. So if you look at this chart, just remember this chart starts in January of 2025. That was only a year and a half ago. Just a few months in, these companies passed Workday, a pretty incredible HR company. Then it was ServiceNow. It was Adobe by the end of the year. Salesforce on the way just in January. Now even bigger than Google Cloud and Azure. So what can that look like in the future? Well, this is just based on kind of some assumptions and some forecasts, but you can see that we estimate that only not only is it bigger than Azure, but by the end of the year could be bigger than AWS and potentially bigger than all of Microsoft by 2028.
而且这还会继续改善。部分原因是,OpenAI 和 Anthropic 的增长速度是我们前所未见的。看这张图,记住,这张图是从 2025 年 1 月开始的。那才是一年半以前。才过了几个月,这些公司就超过了 Workday——一家相当了不起的 HR 公司。然后是 ServiceNow。到年底是 Adobe。刚到 1 月就顺手超过了 Salesforce。现在甚至比 Google Cloud 和 Azure 还大。那未来会是什么样?这只是基于一些假设和预测,但你可以看到,我们估计它不仅比 Azure 大,到年底还可能比AWS 更大,到 2028 年甚至可能超过整个微软。
便签引用
7:20
Now these hyperscalers aren't sitting still. They're seeing the disruption. But actually they're doing more than seeing it, they're actually funding it. Because if you look at the ChatGPT moment that we know happened, look at how much these companies, the largest in the world, have invested in enabling and creating this change. Truly unprecedented. So, I know SpaceX, a lot of people are going to talk about SpaceX, so I thought I would share a little bit of how we as investors think about SpaceX. So that as you think about whether it's a stock that you want to own or you just want to seem smarter at a cocktail party, you can benefit from our knowledge.
这些超大规模云厂商(hyperscalers)当然没有坐以待毙。他们看到了这场颠覆。但实际上他们做的不止是「看到」,他们其实还在出钱资助它。因为如果你看我们都经历过的 ChatGPT 时刻,再看看这些全球最大的公司为了促成和创造这场变革投了多少钱。真的是史无前例。我知道 SpaceX,很多人都会聊 SpaceX,所以我想分享一下我们作为投资人是怎么看 SpaceX 的。这样,不管你是在考虑要不要买它的股票,还是只想在鸡尾酒会上显得聪明一点,都能从我们的研究里获益。
便签引用
05SpaceX 估值框架:发射频次与平台化
8:05
The first thing that pops out when we look and study SpaceX is that the number one driver correlated to the valuation of SpaceX is cadence of launches. Which intuitively makes sense. If your business is the launch business, the more you launch, the higher your value should be. So I think we see that in the data. But there's another fundamentally different ratio that I'm going to point you to, which is what if we took the valuation, we divided it by the number of launches, what would that look like?
我们在研究 SpaceX 时,最先跳出来的一点是:与 SpaceX 估值相关性最高的第一驱动因素,是发射频次。这在直觉上说得通。如果你做的是发射生意,那你发射得越多,你的价值就该越高。我觉得数据里确实能看到这一点。但还有一个本质上很不一样的比率,我想请大家注意,那就是:如果我们把估值除以发射次数,会是什么样?
便签引用
8:38
Well, you can see it was kind of in a fixed range for a while and then it really started to move up. And we believe that markets are rational and so we started thinking, well, why is it that the market is valuing SpaceX uh higher on a per launch basis when it's launching more than when it was just starting out? And my fundamental view, and we'll kind of call this our coat your framework, is that the reason is that the quality of SpaceX's business model increases the more you launch. So in phase one, which we call pre-constellation, you're just trying your rockets. And we know rockets are hard.
你可以看到,它有一段时间基本在一个固定区间里,然后就真的开始往上走了。我们相信市场是理性的,所以我们开始想:为什么在 SpaceX 发射得更多的时候,市场反而给它更高的单次发射估值,比刚起步那会儿还高?我的基本看法——我们姑且称它为我们的框架——是:原因在于 SpaceX 商业模式的质量会随着发射次数增加而提升。在第一阶段,我们称之为「星座前时代」,你只是在试你的火箭。而我们知道,火箭很难搞。
便签引用
9:22
And maybe you have a few government customers and that's a one-time revenue business and it's unpredictable. Then you get into your initial ramp and now you might have one constellation. So why is a constellation important? Well, it's an end market and it's a recurring revenue business. The more satellites you put up, the more subscribers you have, the more revenue, etc. Now, you can move from ramp into scale. Now, you don't just have one constellation, you have multiple constellations. And ultimately, we believe that a wide a wide variety of companies and governments and militaries will want to own their own constellations so they can control their own destiny.
你可能有几个政府客户,那是一次性收入的生意,而且不可预测。接着你进入初期爬坡期,这时你可能有了一个星座。为什么星座重要?因为它是一个终端市场,而且是经常性收入的生意。你发上去的卫星越多,订户就越多,收入也越多,以此类推。接下来,你可以从爬坡期走向规模化。这时你不只有一个星座,而是有多个星座。而且我们最终相信,会有各种各样的公司、政府和军队想要拥有自己的星座,好掌握自己的命运。
便签引用
10:10
So, now you move into being a scaled business, which ultimately becomes a platform. And we know how valuable these platforms are in this technology age. And platform means not only do you have many more customers in your core business, but you also have new businesses. It could be space data centers, it could be the optionality of the moon and Mars and other space applications. Now, we know when defining feature of this era has been how quickly these companies are scaling and if we just look at whether it's the PC or the internet or the mobile, Antarctic in particular is scaling like no other company that we've ever seen.
于是你进入规模化的阶段,而它最终会变成一个平台。我们都知道在这个技术时代,这些平台有多值钱。平台意味着,你不仅在核心业务上有多得多的客户,还会有新的业务。可以是太空数据中心,可以是月球、火星以及其他太空应用带来的期权价值。我们知道,这个时代的一个标志性特征就是这些公司扩张的速度。如果我们对比一下 PC、互联网还是移动互联网时代,Anthropic 的扩张速度是我们见过的任何公司都比不上的。
便签引用
06十倍概率悖论与 Cerebras 长跑
10:58
Now, this was kind of an interesting analysis and this is what I'm I'm curious to kind of discuss with the besties, but we looked at essentially three buckets of companies. And we said, "Okay, within each bucket, what is the likelihood that you will have a 10x?" Which I would view as an investor, maybe not a seed investor like Jay Cal, but for us as growth investors, wow, a 10x is pretty good. They're hard to find. So, the data showed us that if you're a unicorn, the odds of you one day becoming a decacorn are about 8%.
这是一个挺有意思的分析,也是我很想和几位老友聊聊的,我们看的基本上是三类公司。我们问:「好,在每一类里,你实现 10 倍增长的概率有多大?」作为投资人,我会这么看——也许不是像 Jay Cal 那样的种子投资人,但对我们这些成长期投资人来说,哇,10 倍已经相当不错了。这种机会很难找。数据告诉我们,如果你是独角兽,有朝一日成为十角兽(decacorn)的概率大约是 8%。
便签引用
11:34
If you're a decacorn, so that means you're over 10 billion, the odds of you becoming a hundred billion dollar company, not much better. 8% to 13%. But how interesting that if you're a centacorn, hundred billion or more, the odds, and by the way, we're putting in public and private companies, you now have a 31% chance of having had a 10x. This kind of flies, in my opinion, in different than maybe we would have expected. And if we look at how quickly these companies are creating value, this is a chart that I kind of added at the last minute because the data is so fresh, but you can see it typically takes multiple years to go from 500 billion to a trillion in market cap.
如果你已经是十角兽,也就是估值超过 100 亿美元,那你成为千亿美元公司的概率,也没好到哪去。从 8% 到 13%。但有趣的是,如果你已经是「百角兽」(centacorn),也就是 1000 亿美元以上,概率——顺便说一句,我们把上市公司和非上市公司都算进去了——你实现 10 倍的概率就变成了 31%。在我看来,这跟我们原本可能预期的很不一样。再看看这些公司创造价值的速度,这张图是我在最后一刻加进来的,因为数据实在太新了。你可以看到,从 5000 亿美元市值涨到1 万亿美元,通常要好几年。
便签引用
12:26
Well, something happened very recently in the public market, which is that not only did we have three companies do it in the same year, but we had two companies do it in a matter of weeks. So, we can talk about what conclusions to take from that. Now, even as these companies were scaling incredibly quickly from 500 billion to a trillion, we had other companies take a long time to succeed. And this is a company called Cerebras that just went IPO, so I thought it'd be a good candidate. I was very proud to be a board member for a long time and led the series B.
但最近公开市场上发生了一件事:不仅有三家公司在同一年里做到了,还有两家公司是在短短几周内做到的。我们可以聊聊从中该得出什么结论。而就在这些公司以惊人速度从 5000 亿冲向 1 万亿的同时,也有一些公司花了很久才成功。这家公司叫 Cerebras,刚刚 IPO,所以我觉得它是个不错的例子。我很自豪当了很长时间的董事会成员,也领投了它的 B 轮。
便签引用
13:04
But if you look at the company's funding history, you can see why I put the little construction icon, that it took a long time and there were some dark periods, multiple years, of no new capital, of hard grind to develop their technology, all of that time leading up to a massive OpenAI contract, which then quintupled the value of the company. But, we know Cerebras has been successful and frankly, it's not just Cerebras. Semis are on a generational run. I was just talking about this with my friend Brad Gerstner earlier. This is just since 2024, the All-In Summit.
但如果你看这家公司的融资历史,你就明白我为什么放了个小小的施工图标——它花了很长时间,中间有过一些黑暗期,好几年没有新的资本进来,只能苦熬着打磨技术,所有这些时间的积累,最后换来了一份巨额的 OpenAI 合同,公司估值随之翻了五倍。但我们知道 Cerebras 是成功的,而且坦白说,不只是 Cerebras。半导体正处在一轮世代级的行情中。我刚才还在和我的朋友 Brad Gerstner 聊这个。这只是从 2024 年 All-In 峰会以来的数据。
便签引用
07内存需求、AI 收入三支柱与全行业颠覆
13:45
You can see how much the semiconductor industry has outperformed the index. What will happen in the future? Well, one takeaway from having listened to a lot of speakers this morning is that there seems to be wide agreement that the more an AI system knows about your business or you as a user, the more useful it is. You want to know when you go and book a restaurant that it knows already your preferences, whether it's what time you like to eat or what food you like to have, etc. So, we think ultimately that in this era, the amount of memory per user could quintuple just based on the demand that these AI systems are requiring to provide their services.
你可以看到半导体行业跑赢指数的幅度有多大。未来会怎样?听了今天上午这么多位讲者之后,我的一个收获是:大家似乎有一个广泛共识——一个 AI 系统对你的业务、对你这个用户了解得越多,它就越有用。你希望你去订餐厅的时候,它已经知道你的偏好,不管是你喜欢什么时间吃饭,还是你爱吃什么菜,等等。所以我们认为,在这个时代,单个用户所需的内存量最终可能会翻五倍,仅仅是因为这些 AI 系统为了提供服务而产生的需求。
便签引用
14:34
That helps explain why we've seen some of these moves in these memory companies. And then I want to finish on a point that I think has a lot of controversy, which is where's the revenue? If we remember over the past 12 to 24 months, there's been a lot of discussion about is there revenue? Is there ROI? Where is this associated with? So, we tried to look and see, okay, what is the size ultimately of the AI ecosystem? We believe that it's about 140 billion today. It'll be about 300 billion this year and it'll double in 2027. So, where is that revenue coming from?
这也能解释为什么我们看到这些存储公司的股价出现了这样的走势。最后我想讲一个我认为争议很大的点,那就是:收入在哪里?回想过去12到24个月,大家一直在讨论:到底有没有收入?有没有投资回报?这些跟什么挂钩?所以我们试着去看一看,整个AI生态的规模到底有多大?我们认为今天大概是1400亿美元。今年会到3000亿美元左右,到2027年还会翻一倍。那这些收入是从哪来的?
便签引用
15:17
Well, if we break it down, we can see we kind of estimate three key pillars to this industry. One we know, consumer. Number of subs times an ARPU, that gives you your consumer revenue. One that I think a lot of people forget, but it's ads. We estimate currently that about a quarter of ads served by Meta and Google are AI enabled. We think that penetration will eventually go to 100%. That's 150 billion. And then obviously we all know about the breakthroughs in enterprise. And what Claude Code and Codex are doing inside of those businesses. So if you add all these together, you get a good sense of the size of this ecosystem.
如果我们拆开看,可以看到我们大致把这个行业分成三大支柱。第一个大家都知道,消费者端。订阅用户数乘以ARPU,就是你的消费者收入。还有一块我觉得很多人会忽略,就是广告。我们目前估计,Meta和谷歌投放的广告里大约有四分之一是由AI驱动的。我们认为这个渗透率最终会到100%。那就是1500亿美元。然后很明显,我们都知道企业端的突破。以及Claude Code和Codex在这些企业内部正在做的事情。所以把这些加在一起,你就能大致感受到这个生态的规模。
便签引用
16:09
So this will be kind of my second to last slide. One thing that's different to me about this era versus the prior eras in which I was an investor is that almost every sector of the economy is being transformed at the moment. So we know some of the obvious ones, software, but look at Telco. I believe that within a few years Starlink will power a device which will actually enable you to make a phone call anywhere in the world, and we think that's a solved problem, but every time we get a dropped call we get reminded that there's a better technology out there. So back to Nikesh's framework on profit pools, I think the Starlink profit pool is the Telco global profit pool of broadband and wireless.
这大概是我的倒数第二张幻灯片。对我来说,这个时代和我此前做投资人的那些时代有一点不同:几乎经济的每一个板块此刻都在被改造。有些是显而易见的,比如软件,但你看看电信。我相信几年之内,星链(Starlink)就能驱动一种设备,让你真的可以在世界上任何地方打电话,我们以为这个问题已经解决了,但每次电话断线都会提醒我们,其实还有更好的技术存在。所以回到Nikesh关于利润池的框架,我认为星链的利润池,就是全球电信在宽带和无线上的利润池。
便签引用
16:56
We know compute is driving massive changes in semis. We had senators earlier on telling us how data centers have changed the energy equation in Pennsylvania. Just think about the auto business. I'm sure a lot of us followed what happened to Ferrari last week trying to introduce a new technology of electric and autonomous. Begging the question of what is the future of that franchise in an autonomous and electric world and I think the response to that car kind of fed into this narrative. And then obviously in consumer, we know GLPs are having a profound impact on consumption of food, alcohol, composition of diet, and a huge focus kind of on wellness.
我们知道算力正在推动半导体行业的巨大变化。今天早些时候有参议员告诉我们,数据中心如何改变了宾夕法尼亚州的能源格局。再想想汽车行业。我相信我们很多人都关注了上周法拉利试图推出电动化和自动驾驶新技术时发生的事。这就引出一个问题:在一个自动驾驶和电动化的世界里,那个品牌的未来是什么?我认为大家对那款车的反应某种程度上印证了这个说法。再明显不过的是消费领域,我们知道GLP类药物正在深刻影响食品、酒类的消费、膳食结构,以及大家对健康的高度关注。
便签引用
17:44
So, if we put all that together, what are our takeaways? Well, my first takeaway is that the new unicorn economy is healthier. And we really have kind of AI to thank for that. The winners are compounding faster than ever, which means the cost of not being in a winner are higher than ever. Disruption is impacting every part of the global economy. And by the way, we don't even have super intelligence yet. So, if I think that it was about 2 years since my last All-In Summit, I started thinking, well, gee, what could this look like in 2 years? And we know it's going to be a really interesting time, and thankfully, we have a great group to help us navigate what the next 2 years will look like.
所以把这些放在一起,我们的结论是什么?我的第一个结论是,新一代独角兽经济更健康了。这真的要感谢AI。赢家的复利增长比以往任何时候都快,这意味着没押中赢家的代价也比以往任何时候都高。颠覆正在影响全球经济的每一个部分。顺便说一句,我们甚至还没有超级智能。所以,想到距离我上一次参加All-In峰会大概已经两年了,我就开始想,天哪,两年后会是什么样?我们知道那会是一段非常有意思的时期,而且很幸运,我们有一群很棒的人来帮我们看清未来两年会是什么样。
便签引用
08圆桌:幂律之下资本该去哪
18:32
We're going to give this a title, the power law rules our lives. The power law rules our lives. All the great gains are being consolidated into small numbers of companies. Uh but we're still seeing strength in those. How do you see the private market uh ecosystem, the game on the field, evolving because of the stay private longer and these extraordinary outcomes. Obviously, I operate in the earliest stages. You have people who are doing Series A's like Craft Ventures. You have uh yourselves dipping down into private, but I was talking to Brad Gerstner, who you um discussed earlier. He was like, I I I have to figure out where to put my time.
我们给这一节起个标题:幂律主宰我们的生活。幂律主宰我们的生活。所有巨大的收益都在向少数几家公司集中。呃,但我们在这些公司身上仍然看到强劲的势头。你怎么看私募市场这个生态、这场牌局,因为公司更长时间保持非上市状态和这些超常回报,会怎么演变?显然,我做的是最早期。有像Craft Ventures这样做A轮的人。也有呃像你们这样往下做到私募的。但我之前跟Brad Gerstner聊,就是你们前面提到的那位。他说,我得想清楚把时间花在哪儿。
便签引用
19:14
You know, we have early stage and and they and they do obviously public like yourselves. So, and then add to that, you have people like Andreessen Horowitz maybe going for the average in a major way and indexing venture. What what is the playing field going to look like for people who are LPs, angel investors, venture firms? What How does this all sort out into a cohesive strategy over the next decade or two? Because it's clearly the private markets are operating much differently than the playbook 20 years ago.
你知道,我们有早期,他们也明显做公开市场,像你们一样。所以,再加上,还有像Andreessen Horowitz这样可能在大规模地去赚平均收益、把风投指数化的。那么对于LP、天使投资人、风投机构来说,这个赛场会变成什么样?这一切在未来一二十年里要怎么整合成一套连贯的策略?因为私募市场的运作方式,显然已经和20年前的打法很不一样了。
便签引用
19:45
>> Yeah, so I think the the first breakdown I would I would submit is on the positive side of the ledger, the outcomes are big, right? We're seeing outcomes that we never thought possible in private companies. And I think that's good just generally for our ecosystem. So, we have big outcomes. It's really why I wanted to kind of show that SpaceX slide. It was somewhat counterintuitive to me on the launch business. Why is it that the company would be valued more as it launched more? So, I think at least we have a number of big outcomes.
>> 是的,我认为第一层拆解是:先说好的一面,回报体量很大,对吧?我们看到私营公司里出现了我们过去认为不可能的回报。我觉得这对我们整个生态总体来说是好事。所以,我们有大的回报。这也正是我想放那张SpaceX幻灯片的原因。发射业务这块对我来说有点反直觉。为什么一家公司发射得越多,估值反而越高?所以我觉得,至少我们现在有一批大体量的赢家。
便签引用
20:17
And those outcomes will be public within, it seems like a 12-month period. So, if I think about, you know, the ZIRP era where the outcomes were smaller and companies were not going public, I think at least in this era, we have big outcomes and a desire of these companies to go public. Right? I think both Anthropic and OpenAI are both publicly saying that they want to be public. So, I would say that's good. I'd say the biggest issue is the It seems like we're talking about K-shape and power law in every aspect of life.
而且看起来这些公司会在12个月内上市。所以,如果我想想零利率(ZIRP)那个时代,回报更小、公司也不上市,我认为至少在这个时代,我们有大的回报,而且这些公司有上市的意愿。对吧?我觉得Anthropic和OpenAI都在公开表示他们想上市。所以我会说这是好事。我想说最大的问题是……好像我们在生活的每个方面都在谈K型分化和幂律。
便签引用
20:52
>> Yeah. >> And it seems like that's the case in startups as well. So, we've seen, if you looked at my centacorn slide, we've really kind of been stuck at this number for a little bit now. So, I think Jay Kyle, I think the point that you're asking is if we were to see no new centaurs horns right in the next decade, we've basically not really seen any new one in the past couple of years. I think that's going to be a warning sign kind of for us. >> What does this mean for where capital allocators should be thinking about putting their money? Because what you're showing here, a rational person who's an LP, would just say wait for whoever gets to a hundred billion and yolo every dollar you can in there cuz it's the most sure thing, it's the least brittle, it's the least amount of effort, and it's the quickest return.
>> 是的。>> 而且看起来创业公司也是这样。所以我们看到,如果你看我那张“百角兽”(centacorn)的幻灯片,我们其实已经在这个数字上卡了一阵子了。所以我觉得,Jason,我想你问的重点是:如果未来十年我们看不到新的百角兽出现——过去这几年我们基本上就没真正见到一家新的——我觉得那对我们来说会是一个警示信号。>> 那这对资本配置者该把钱投向哪里意味着什么?因为你这里展示的东西,一个理性的LP会说:那就等谁做到一千亿估值,然后把能投的每一块钱都全仓押进去,因为那是最确定的、最不脆弱的、最省力的,也是回报最快的。
便签引用
21:41
But as we know, supply demand equals valuation. These valuations are disconnecting from any valuation metric we've ever had. Uh we had it explained to us today by Bill Ackman, I think quite accurately. You're making venture investments in trillion-dollar companies and giving them 50 times revenue, 100 times revenue valuation. So talk a little bit about where people should rationally, as a limited partner, as a private investor, a high-net-worth individual, ultra-high-net-worth, where should they be putting their money to work?
但我们都知道,供需决定估值。这些估值正在脱离我们以往任何一种估值指标。呃,今天Bill Ackman给我们解释过,我觉得说得挺准的。你是在对万亿美元级的公司做风险投资,给它们50倍收入、100倍收入的估值。所以聊一聊,作为有限合伙人、作为私人投资者、作为高净值或超高净值人士,理性来说他们应该把钱投到哪里?
便签引用
09公开市场是消毒剂:估值与审视
22:11
And do you worry about this everybody racing to be in three names? >> Yeah, look, that obviously was the right strategy for the past five years. The question is about the next five years. >> Correct. >> Right? So the one pushback I would have just on the valuation argument is these are not fake companies. >> No, absolutely not. >> I think we have to I remember the bubble of 2000. I also remember 2021. Right? These are companies generating substantial revenue at scale that are growing faster than anything we've ever seen. So, you know, these businesses are real and they're performing, and I think it was widely shown that Anthropic even had a profitable month, I believe is what was reported. So, you know, they're they're also kind of profitable.
你会不会担心所有人都挤着去押那三家公司?>> 是的,你看,过去五年这显然是正确的策略。问题在于接下来的五年。>> 没错。>> 对吧?不过对估值这个论点,我唯一想反驳的是:这些不是空壳公司。>> 对,绝对不是。>> 我觉得我们得……我还记得2000年的泡沫。我也记得2021年,对吧?这些公司在很大规模上产生着可观的收入,增速比我们见过的任何东西都快。所以你知道,这些生意是真实的,而且业绩在兑现。我记得有广泛报道说,Anthropic甚至已经有一个月是盈利的,报道是这么说的。所以你知道,它们某种程度上也是盈利的。
便签引用
23:00
But ultimately, and I think Chamath, you agree with this, the public market is the great test >> equalizer. >> Yes. >> Yeah. >> The scale. It will be the great antiseptic. It will not care about my presentation or, you know, um and so I love that. I love that these companies are going to have to face the scrutiny, both SpaceX, OpenAI, and Anthropic, of the market, right? And ultimately, I'm a big believer in the market. And so I'm very excited to see these companies go public, withstand the scrutiny of short sellers, pontificators, debaters, politicians, kind of etc.
但归根结底——Chamath,我想你也同意——公开市场才是最好的检验 >> 拉平器。>> 是的。>> 对。>> 那个量级。它会是最好的消毒剂。它不会在乎我的演示,你知道,嗯,所以我很喜欢这一点。我很喜欢这些公司将不得不接受市场的审视,SpaceX、OpenAI和Anthropic都一样,对吧?而且归根结底,我是市场的坚定信仰者。所以我非常期待看到这些公司上市,去经受做空者、夸夸其谈者、辩论者、政客等等的审视。
便签引用
23:43
>> Let me Let me ask you two questions on that. The first is very tactical, which is normally we would say that the antiseptic or the disinfectant happens on T equals one day, right? >> Yeah. >> Now the rules are changing. There's going to be a lot of passive buying. So it's going to move out that date cuz you're going to have to wash through a lot of supply demand. So that's that could maybe >> Six month plus one. >> Six month plus one is when you'd say we can really start to get a sense of what these companies are.
>> 我我就这个问你两个问题。第一个很具体、很战术,就是通常我们会说,那种消毒、杀菌的作用发生在上市第一天,对吧?>> 是的。>> 现在规则变了。会有大量被动资金买入。所以那个日期会往后推,因为你得先把大量的供需关系消化掉。所以那可能 >> 六个月零一天。>> 六个月零一天,才是你会说我们真正开始看清这些公司到底是什么的时候。
便签引用
24:12
>> Okay, so that's a tactical question. The more strategic question, Thomas, is do you think that there's something structurally inefficient or wrong that's allowing these compounders to accelerate at scale? Like is that a market efficiency problem or do you think that's just a survivor bias and we shouldn't look too much into that? How do you look at that? >> I don't want to read too much into it because the end of those companies is so small and look at Anthropic, right? Anthropic pre-Claude code was a completely different company than post-Claude code, right? So one one event completely dented the trajectory of almost that entire industry.
>> 好,那是战术层面的问题。更战略层面的问题是,Thomas,你觉得是不是存在某种结构性的低效或者不对劲的东西,在让这些复利增长的公司在如此大的规模上还在加速?这是一个市场效率的问题,还是你觉得这只是幸存者偏差、我们不该过度解读?你怎么看?>> 我不想过度解读,因为这类公司的样本太小了,而且你看Anthropic,对吧?Claude Code之前的Anthropic和Claude Code之后的Anthropic,完全是两家不同的公司,对吧?所以一个事件就彻底改变了几乎整个行业的轨迹。
便签引用
24:46
So it's hard for me to know whether that's truly, you know, whether these companies were like the mule in the Foundation series, something that could never be predicted and just came out of nowhere and it was just a one-time thing. You know, um we'll see. I do think that the narrative of oh, these models are commodities and these companies are going to get I think that's been pretty thoroughly disproven now. Right? Um and >> How do you as you know, your asset base has swelled, you've gone into you've expanded strategy, you're now doing you know, data centers, you're doing many things.
所以我很难判断那到底是不是真的……这些公司是不是像《基地》系列里的“骡”那样,完全无法预测、凭空冒出来,而且只是一次性的偶然。你知道,嗯,走着看吧。我确实认为,那种“哦,这些模型就是大宗商品,这些公司会(被商品化)”的说法,我觉得现在已经被相当彻底地证伪了。对吧?嗯,还有 >> 你是怎么……你知道,随着你的资产规模膨胀,你进入了……你扩展了策略,现在你在做数据中心,做很多事情。
便签引用
25:21
How do you keep it all organized when maybe a slide like that would say, "Hold on a second, maybe we should have just plowed $10 billion into Micron?" Like how do you balance that >> reason I I make a deck like this and in some ways I should thank you guys because when we when I do something like this for you guys and it is tremendous amount of time from uh myself and our team and um we really want to present you with accurate information. So, the past 2 weeks has pretty much been a full-time job doing this.
你怎么把这一切理清楚?毕竟像那样一张幻灯片可能会说,“等一下,也许我们当初就该把100亿美元全砸进美光(Micron)?”你怎么平衡这个 >> 我做这样一套PPT的原因……某种程度上我该谢谢你们,因为当我为你们做这种东西的时候,那要花掉我和我们团队大量的时间,嗯,我们真的很想给你们呈现准确的信息。所以过去两周基本上就是全职在做这件事。
便签引用
25:51
But, for me it re-anchors my conviction around what to do. You know, I I can't go and listen to a thousand people and then I get distracted and I I don't know what I'm thinking anymore. So, going back to these ground truths of numbers and valuation bring me back to a point of okay, conviction. Right? So, for me whenever I try and understand the world, I go back to okay, what do I understand? I understand models, I understand numbers. Let me go back and kind of peel this out. What I think hopefully the deck will show is, "Look, there is substantial reasons for why right? If you look at the the trillion-dollar companies that became trillion-dollar companies in a matter of weeks, these are not fake companies. Like these companies have been around for decades, right? And they trade at the lowest multiple of earnings of the S&P 500 of almost any other company.
但对我来说,它重新锚定了我对该做什么的信念。你知道,我不能去听一千个人说话,然后被带偏,最后自己都不知道自己在想什么了。所以回到这些数字构成的基本事实和估值让我重新回到一个确定感、一种信念的状态。对吧?所以对我来说,每当我试着理解这个世界的时候,我就回到一个问题:我到底懂什么?我懂模型,我懂数字。那我就回过头来,把这些一层层剥开。我希望这份材料能说明的是:"你看,这背后是有扎实原因的。"对吧?如果你看看那些在短短几周内就变成万亿美元市值的公司,它们不是什么虚的公司。这些公司已经存在几十年了,对吧?而且它们的市盈率是标普500里几乎最低的。
便签引用
26:43
So, there is kind of something kind of real happening. >> energy there that just got released. >> Correct. And now it's like, "Well, someone made a point to me on on um on uh you'll like this on memory, right?" They said well if if I want to design a chip like open AI, I can go to TSMC. And I know it's hard, but at least I have TSMC to help me. If I want to make memory, well there is no TSMC. >> Right. >> So what should the memory multiples be versus ASIC chips as an example? >> The wrath of Lina Khan can be seen seen clearly in this and Zach's I want to get your input into how policy and elections matter when it comes to outcomes.
所以确实是有一些真实的东西在发生。>> 那里积蓄的能量刚刚被释放出来了。>> 没错。现在的情况是——有人跟我讲过一个观点,关于存储芯片的,你会喜欢这个说法。他们说:如果我想像 OpenAI 那样设计一颗芯片,我可以去找台积电。我知道这很难,但至少我有台积电可以帮我。可如果我要做存储芯片,那是没有"台积电"的。>> 对。>> 那么举例来说,存储芯片的估值倍数相对于 ASIC 芯片,应该是多少呢?>> 从这里可以清楚看到莉娜·汗(Lina Khan)带来的冲击。Zach,我想听听你的看法:政策和选举对最终结果有多大影响。
便签引用
10万亿俱乐部的筛选机制与垄断天花板
27:18
>> As I saw, I don't know if it was this chart, but the the chart where you show the odds of each category reaching the next level. The >> Would you have predicted that out out of curiosity? >> very counterintuitive. Where I mind went was extrapolating one more, which is what are the odds that trillion dollar market cap companies get to 10? >> Yeah. >> Yeah. >> And the last one was 31%. I mean it seems to me would be like 50%? 100%? I don't know. It seems I'm thinking is it going to be greater than or less than 30? And it seems to me it's greater than 30% are going to hit that.
>> 我看到的——我不确定是不是这张图——就是你展示每一类公司迈向下一个层级概率的那张图。那个 >> 你当时会预测到这个结果吗,我只是好奇?>> 非常反直觉。我当时想的是再往外推一步:万亿美元市值的公司涨到十万亿的概率有多大?>> 是啊。>> 对。>> 最后一档是 31%。我的感觉是,这个数字应该像 50%?100%?我也说不好。我当时在想,这会高于还是低于 30%?我觉得会有超过 30% 的公司能达到那个水平。
便签引用
27:51
>> It's It's It's probably the filtering mechanism of what's the compounding advantage or the durability of earnings of that company. And for every step you have a filter that says, do you have a compounding advantage? Do you increase Do you have a stronger durability of earnings? And if so, you're going to accelerate to the next phase. It's almost like fundamental to business um valuation analysis, like Ben Graham style analysis. >> To get to that level that's called the trillion dollar club, you have to have a dominant business. And then the question is just at what point do you hit saturation? And it seems like all of these markets have ended up being so much bigger than anyone would have predicted.
>> 这大概是一种筛选机制,看的是这家公司复利型优势有多强、盈利的持久性有多好。每往上走一步,就有一道筛子问你:你有没有复利型优势?你有没有更强的盈利持久性?如果有,你就会加速进入下一个阶段。这几乎就是商业估值分析里最基本的东西,就是本·格雷厄姆那一套分析方法。>> 要进入所谓的"万亿美元俱乐部",你必须有一个占据主导地位的业务。那么问题就变成你在什么时候会触及饱和。而看起来所有这些市场最后都比任何人预想的要大得多。任何人能预测的。
便签引用
28:29
>> Yeah. >> I mean just >> And monopoly or or government intervention cuz fundamentally if you think about the breakup of the Bell system, I mean who knows where that would have gone over time. They could have had a monopoly on the internet. They could have had a monopoly on commerce. They could have had a monopoly e-commerce and on and on and on. >> But but as a trading strategy, what you'd like to do is have a bot that just starts buying up shares of a company once it hits 1 trillion. >> [laughter] >> And actually, if you had done that, I mean, a lot of the >> I remember who Who was the first company to hit a trillion? Was it Apple?
>> 是啊。>> 我是说,只是 >> 还有垄断,或者政府干预。因为从根本上说,如果你想想当年拆分贝尔系统这件事,谁知道那家公司后来会走到哪一步。他们可能会垄断互联网,可能会垄断商业,可能会垄断电商,等等等等。>> 但作为一种交易策略,你会想做的是搞一个机器人,一旦某家公司市值突破 1 万亿,就开始不停买入它的股票。>> [笑声] >> 而且如果你真这么干了,其实很多 >> 我在想,第一家市值突破万亿的公司是谁?是苹果吗?
便签引用
28:57
>> I believe so, yeah. >> Yeah, and then everyone was like, "Oh my god, well, you know, now there's what, like five or something?" >> Well, by the way, that's what I >> study that showed if you bought I'm sorry to interrupt, but that if you bought the Nasdaq um over a 10-year period, you get like a 3x multiple or something quite significant. You just rebalanced every year on the top 10 companies in the Nasdaq. So, just buy the top 10 companies by market cap and you outperform over a decade by like 3x.
>> 我记得是的。>> 对,当时所有人都在说:"天哪,现在有多少家来着,五家左右了吧?">> 顺便说,这正是我 >> 有个研究显示,如果你买入——不好意思打断一下——如果你买纳斯达克,在 10 年里,你大概能拿到 3 倍左右的回报,相当可观。你只要每年重新平衡一次,持有纳斯达克市值最大的前 10 家公司。就是按市值买前 10 大公司,十年下来你能跑赢大盘大概 3 倍。
便签引用
11资本回流、SpaceX 定价与价格战
29:20
>> Yeah, Thomas, why didn't you do that? What is your maybe maybe just the last question so we make sure we wrap up about something that I think you are uniquely positioned to tell us. What happens when all this money gets distributed back? Like, what do you think happens to your competitive dynamics? What do you think happens to entrepreneurial dynamics? What happens in Silicon Valley when three or four trillion dollars gets put back to GPs, then to LPs, and then the recycling happens? >> Well, the first thing that comes to mind is I remember when David was so bearish California real estate um >> [laughter] >> We'll see whether this influx of capital uh >> Time to sell.
>> 是啊,Thomas,你当初怎么没这么干?最后一个问题吧,这样我们好收尾。我觉得这个问题你特别有资格回答:当所有这些钱被分配回去之后,会发生什么?比如说,你觉得竞争格局会怎么变?创业生态会怎么变?当三四万亿美元回流到 GP,再到 LP,然后开始循环再投资的时候,硅谷会发生什么?>> 嗯,我第一个想到的是,我记得当年 David 对加州房地产有多看空 >> [笑声]>> 我们看看这波资金涌入会不会 >> 该卖了。
便签引用
29:59
>> San Francisco homes are still >> Yeah, maybe buy the mausoleum. >> Anybody Anybody interested in a 40,000 square foot mausoleum? >> [laughter] >> Protesters not included. >> The one thing I'll say on SpaceX, and look, I don't know whether 1.75 is the right price for the IPO, and you know, frankly, I have no clue. What I do know is that the global profit pool of telco and service providers across the world is anywhere between two to 400 billion, depending on who you want to address, right? So, you do have to think about a company that just in a core business, which by the way wasn't even in a couple years ago, is addressing a profit pool of multiple hundreds of billions of dollars with a substantially better product, right? I think all of us, when you think about Starlink works all the time, no radio towers, you know, etc.
>> 旧金山的房子还是 >> 是啊,也许该买那座陵墓。>> 有没有人对一座四万平方英尺的陵墓感兴趣?>> [笑声] >> 抗议者不含在内。>> 关于 SpaceX 我要说一点。说实话,我不知道 1.75(万亿)是不是 IPO 的合理定价,坦白讲,我完全没概念。我知道的是,全球电信和服务运营商的利润池,总共大概在 2000 亿到 4000 亿美元之间,取决于你想覆盖哪一块,对吧?所以你得想想,这家公司光是核心业务——顺便说,这块业务几年前根本还不存在——就在切入一个好几千亿美元规模的利润池,而且产品要好得多,对吧?我想我们所有人都能体会,Starlink 随时随地都能用,不需要信号塔,等等。
便签引用
30:47
So, I go back to it and I think it's hard to know, Chamath, cuz we've never had anything like this before, right? Um the ultimate question would be if you look a bit in the in the ride-sharing wars and in food delivery wars, at some point that excess capital was used to have a price war. >> Right. >> Could we see a price war between OpenAI and Anthropic as a question, right? If these companies have so much capital, is one of them ever going to pull a price lever to try and compete with the other?
所以我回过头来想,Chamath,我觉得这很难判断,因为我们以前从来没遇到过这样的事,对吧?终极问题是,如果你回看一下网约车大战和外卖大战,到某个时点,那些过剩的资本就被拿去打价格战了。>> 对。>> 我们会不会看到 OpenAI 和 Anthropic 之间打价格战?这是个问题,对吧?如果这些公司手里有这么多资本,其中一家会不会某天动用价格这个杠杆,去和另一家竞争?
便签引用
31:20
>> Rationally, they should. >> They should. So, we might see things that we can't predict today, right? Where companies might say, "Well, I have my 200 billion of cash." Now, the issue is they're spending so much on infrastructure, right? So, it's it's not obvious, but I do think we're going to see some counterintuitive um changes. You guys will discuss them on the show every week, and hopefully I'll come back in 2 years and and analyze what went right and what went wrong. >> Honestly, I think what should happen is you should come back here every year and we should get the benefit of >> Yeah, let's lock it in.
>> 理性来说,它们应该会。>> 应该会。所以我们可能会看到一些今天预测不到的事情,对吧?比如有公司会说:"我手上有 2000 亿现金。"不过问题在于,它们在基础设施上的开销太大了,对吧?所以这不那么显而易见,但我确实觉得我们会看到一些反直觉的变化。你们每周在节目里会讨论这些,希望两年后我能再回来,分析一下哪些判断对了、哪些错了。>> 说真的,我觉得应该这样:你每年都回来一次,让我们受益于>> 对,就这么定了。
便签引用
12收尾致谢
31:53
>> We'll lock it in. >> We'll pay We'll pay We'll pay We'll pay for the two years. >> pay for the two weeks of work that's done. >> [laughter] >> Which we really appreciate, by the way. >> Really do appreciate the work and the effort. I know it's a lot. Yeah. >> And it's it's really great to have you bring this to the audience. >> It just shows also the power of sometimes slowing down >> Yeah. >> and to meditate on you know, the the actual state of reality, and it was incredibly grounding. >> Incredibly rich coming from you.
>> 我们就这么定了。>> 我们付钱、我们付钱、我们付钱、我们会付这两年的钱。>> 付这两周工作量的钱。>> [笑声] >> 顺便说一句,我们真的非常感激。>> 真的很感谢你的付出和努力。我知道工作量很大。是啊。>> 而且你能把这些带给观众,真的太棒了。>> 这也说明了有时候慢下来是很有力量的 >> 是啊。>> 静下心来思考现实的真实状态,这特别让人踏实。>> 从你嘴里说出来,特别有分量。
便签引用
32:15
Incredibly grounding. >> I think it's a compliment or an insult. I'm >> Compliment to Thomas. >> enough to know. >> Thank you. >> I'll just say thank you. >> To you, Chamath, for that incredible compliment, and for you, Thomas, for coming. Thank you. >> [applause] [music] >> Thanks, bro. Yeah, thanks. Great job, guys.
特别让人踏实。>> 我不确定这是夸奖还是讽刺。我 >> 这是在夸 Thomas。>> 还没法判断。>> 谢谢。>> 我就说一句谢谢。>> 谢谢你,Chamath,给了这么高的评价;也谢谢你,Thomas,能来。谢谢。>> [掌声] [音乐] >> 谢了,兄弟。是啊,谢谢。干得漂亮,各位。
便签引用
32:38
>> [music] [music] >> Woo!
>> [音乐][音乐] >> 哇哦!
便签引用
视频总结 · 一句话概括与核心要点

一句话概括

Coatue 创始人 Thomas Laffont 在 All-In 峰会上用数据论证:AI 让独角兽生态比 ZIRP 时代更健康,但价值高度集中于极少数"百亿美元级"公司,SpaceX、OpenAI、Anthropic 即将到来的 IPO 将一举返还超过过去十年总和的现金,而幂律法则正统治整个创投与公开市场。

核心要点

  • 独角兽经济已回暖,但"少而精"成为新常态。 自 2024 年 9 月以来独角兽整体估值上涨约 70%,公开市场同步上涨。AI 连续多年蚕食融资份额,但新独角兽数量已从 2021 年 ZIRP 峰值回落到疫情前水平,导致单个独角兽平均融资额较 2021 年增长 5 倍。
  • 2021 年群组是生态健康的反面教材。 ZIRP 之前的 73 家独角兽在成为独角兽 20 个季度后,80% 完成了新一轮融资或退出;而 2021 年的 479 家独角兽同期完成率不到 20%。2024 年 AI 群组未来更像哪条曲线,是评估生态的关键问题。
  • "Magnificent Eight"私营指数已接近 4 万亿美元。 SpaceX、Stripe、Anthropic、Databricks、Revolut、ByteDance、Anduril 等横跨互联网、AI、金融科技、太空科技,几乎每一家都跑赢了传统 Mag 7。融资进一步向前十名集中,本质是 OpenAI 与 Anthropic 的巨额融资。
  • 退出正在解冻,三家 IPO 将修复十年的现金失衡。 2026 年退出规模已接近 2021 年水平,且还未计入 SpaceX(数周内 IPO)、Anthropic(当天传出秘密递交 S-1)和 OpenAI。三家合计返还的现金将超过过去十年总和,扭转 2024 年他首次在峰会上指出的"消耗远大于返还"的失衡。
  • OpenAI 与 Anthropic 的增长速度史无前例。 从 2025 年 1 月起算,一年半内两家营收先后超越 Workday、ServiceNow、Adobe、Salesforce,如今已超过 Google Cloud 和 Azure;Coatue 预测年底可能超过 AWS,2028 年可能超过整个微软。超大规模云厂商在 ChatGPT 时刻之后的资本开支,实际上是在资助颠覆自己的力量。
  • SpaceX 估值的 Coatue 框架:发射越多,商业模式越优质。 估值与发射频次强相关,且"每次发射对应的估值"持续上升。逻辑是四阶段跃迁:星座前期(一次性政府订单)→ 单星座(订阅制经常性收入)→ 多星座(企业、政府、军方各自拥有星座)→ 平台(太空数据中心、月球火星等新业务)。Starlink 瞄准的是全球电信 2000~4000 亿美元的利润池,且产品显著更优。
  • 规模越大反而越容易再翻十倍。 独角兽成长为百亿公司的概率约 8%,百亿成长为千亿约 8%~13%,但千亿级公司(含公开与私营)达成过 10 倍回报的比例高达 31%。近期公开市场三家公司同年从 5000 亿冲到 1 万亿,其中两家仅用数周,而它们是存在数十年、市盈率位于标普最低档的老牌公司。
  • AI 收入并非虚构,三大支柱支撑。 Coatue 估算 AI 生态收入目前约 1400 亿美元,今年约 3000 亿,2027 年再翻倍。三大来源:消费端订阅(用户数 × ARPU)、广告(Meta 和 Google 约四分之一广告已由 AI 驱动,渗透至 100% 意味着 1500 亿)、企业端(Claude Code 与 Codex 的突破)。Anthropic 据报道已出现盈利月份。
  • 半导体与内存迎来世代级行情。 Cerebras 经历多年无融资的"黑暗期"后靠 OpenAI 大单估值翻五倍。AI 系统越了解用户越有用,每用户内存需求可能增长 5 倍;且造芯片有台积电可依赖,造内存"没有台积电",这解释了内存公司的估值溢价。
  • 颠覆遍及所有行业,且超级智能尚未到来。 软件之外:Starlink 将吞噬电信利润池、数据中心改写宾州能源方程、法拉利新车遭冷遇引发对自动驾驶电动时代品牌前途的质疑、GLP-1 药物重塑食品与酒精消费。结论是"赢家复合增长快于以往,不在赢家里的代价前所未有"。

结论与值得注意的细节

  • 公开市场是"最终消毒剂"。 Laffont 明确欢迎 SpaceX、OpenAI、Anthropic 接受做空者、政客和评论者的审视,但 Chamath 指出被动买盘会推迟真正的价格发现,共识是 IPO 后约 6 个月零 1 天才能看清真实估值。
  • "模型是商品"的叙事已被证伪。 Anthropic 在 Claude Code 之前和之后判若两家公司,一个事件改变了整个行业轨迹,Laffont 将其比作《基地》系列中不可预测的"骡"。
  • 警示信号:千亿级公司数量停滞。 过去几年几乎没有新的千亿级公司诞生,若未来十年仍无新成员,将是生态的危险信号。
  • 对 SpaceX 1.75 万亿 IPO 定价,他坦言"不知道是否合理",只强调其核心业务几年前甚至不存在,如今却在用更好的产品攻击数千亿利润池。
  • 潜在的反直觉变化:价格战。 参照网约车与外卖大战,手握数千亿现金的 OpenAI 与 Anthropic 理性上应当打价格战,但巨额基础设施开支让这一点并不确定。
  • 他做这份报告的动机是"重新锚定信念":听一千个人的观点会让人迷失,回到数字和模型才能恢复判断力。Chamath 评价这是"极其扎实的落地(grounding)"。
  • 一个有趣的交易策略: 嘉宾提到只要按市值买入 Nasdaq 前十名并每年再平衡,十年可跑赢指数约 3 倍;戏言"公司一到万亿就让机器人自动买入"。
  • 双方约定 Laffont 每年回到峰会复盘"哪些判断对了、哪些错了"。
核心句型 · 9
1. The more X, the higher/more Y should be
“If your business is the launch business, the more you launch, the higher your value should be.”
双重比较级表正相关,用 should 表示「按理应当」,弱化绝对断言。适合陈述直觉逻辑后再引出反例,如后文 per-launch 估值上升。
2. Not quite where X was, but pretty good.
“2026 is actually on a pretty good trend. Not quite where 2021 was, but pretty good.”
先让步再肯定的口语化对比结构,省略主语直接接比较对象。适合汇报数据时既承认差距又给出正面判断。
3. On the positive side of the ledger, …
“The first breakdown I would submit is on the positive side of the ledger, the outcomes are big”
借「账本正面」引出利好一面,隐含随后会讲负面。比 on the one hand 更有画面感,商业与投资讨论中常见。
4. X was the right strategy for the past N years. The question is about the next N years.
“That obviously was the right strategy for the past five years. The question is about the next five years.”
用时间对照把讨论从「回顾正确性」转到「前瞻不确定性」,既认可对方前提又不承诺其可延续,是委婉转移争点的利器。
5. The one pushback I would have … is …
“So the one pushback I would have just on the valuation argument is these are not fake companies.”
限定式反驳:先说只有一点异议,再给出核心反论。语气克制,适合会议中对权威观点提出不同意见。
6. I don't want to read too much into it because …
“I don't want to read too much into it because the end of those companies is so small”
read into 表「过度解读」,用否定态度声明再给原因,是表达谨慎、拒绝从小样本下结论的标准句式。
7. I have no clue. What I do know is that …
“Frankly, I have no clue. What I do know is that the global profit pool of telco … is anywhere between two to 400 billion”
先坦承不知,再用强调结构 what I do know 转到自己有把握的事实。适合回答估值、预测类难题时划清知与不知的边界。
8. Begging the question of what …
“Begging the question of what is the future of that franchise in an autonomous and electric world”
口语中表「由此引出一个问题」(严格逻辑学含义为循环论证)。用现在分词短语衔接上文事件与其带来的疑问,行文紧凑。
9. A pre-X was a completely different company than post-X.
“Anthropic pre-Claude code was a completely different company than post-Claude code”
用 pre-/post- 前缀把一个事件设为分水岭,强调质变。可套用于描述任何转折点前后的差异。
词汇精讲 · 103 · 按出现顺序
ankle biters phr. 0:00
(俚)小角色、不足为惧的小竞争者;原意为「咬脚踝的小狗」
flagship /ˈflæɡʃɪp/ n./adj. 0:00
旗舰(产品、基金),指最重要、最具代表性的
hedge /hedʒ/ n. 0:00
对冲;hedge fund 对冲基金
plateaued /plæˈtoʊd/ v. 0:55
进入平台期、增长停滞
wallet share phr. 0:55
钱包份额,指在客户(或市场)总支出中占据的比例
ZIRP /zɜːrp/ n. 1:33
零利率政策(Zero Interest Rate Policy)的缩写
cohort /ˈkoʊhɔːrt/ n. 1:33
(统计)同期群体,同一时间进入某状态的一批对象
exited /ˈeksɪtɪd/ v. 1:33
(投资)退出,即通过上市或被收购实现变现
rounds /raʊndz/ n. 2:33
融资轮次
crushed /krʌʃt/ v. 4:11
(口)碾压、远远胜过
thawing /ˈθɔːɪŋ/ v. 4:11
解冻、回暖(比喻市场活动恢复)
S-1 n. 4:53
美国公司 IPO 前向 SEC 提交的注册说明书
totality /toʊˈtæləti/ n. 5:34
总体、全部
liquidity events phr. 5:34
流动性事件,指上市或被收购等让股东可变现的事件
hyperscalers /ˈhaɪpərˌskeɪlərz/ n. 7:20
超大规模云服务商(微软、亚马逊、谷歌等)
sitting still phr. 7:20
坐视不动、无所作为
unprecedented /ʌnˈpresɪdentɪd/ adj. 7:20
史无前例的
cadence /ˈkeɪdns/ n. 8:05
节奏、频次(此处指发射频率)
constellation /ˌkɑːnstəˈleɪʃn/ n. 8:38
卫星星座,指协同工作的一组卫星
recurring revenue phr. 9:22
经常性收入,如订阅费,可持续、可预测
ramp /ræmp/ n. 9:22
爬坡期,业务快速上量阶段
optionality /ˌɑːpʃəˈnæləti/ n. 10:10
期权价值,指保留未来多种可能性所带来的价值
buckets /ˈbʌkɪts/ n. 10:58
(分析)分组、类别
decacorn /ˈdekəkɔːrn/ n. 10:58
十角兽,估值超 100 亿美元的非上市公司
centacorn /ˈsentəkɔːrn/ n. 11:34
百角兽,估值超 1000 亿美元的公司
market cap phr. 11:34
市值(market capitalization)
led the series B phr. 12:26
领投 B 轮融资
grind /ɡraɪnd/ n. 13:04
苦熬、艰苦而枯燥的长期努力
quintupled /ˈkwɪntʊpld/ v. 13:04
增至五倍
generational run phr. 13:04
世代级行情,几十年一遇的上涨周期
Semis /ˈsemiz/ n. 13:04
半导体股(semiconductors 的简称)
outperformed /ˌaʊtpərˈfɔːrmd/ v. 13:45
跑赢、表现优于
takeaway /ˈteɪkəweɪ/ n. 13:45
要点、收获
ROI n. 14:34
投资回报率(return on investment)
pillars /ˈpɪlərz/ n. 15:17
支柱、核心组成部分
subs /sʌbz/ n. 15:17
订阅用户(subscribers 的简称)
ARPU n. 15:17
每用户平均收入(average revenue per user)
penetration /ˌpenəˈtreɪʃn/ n. 15:17
渗透率
Telco /ˈtelkoʊ/ n. 16:09
电信运营商(telecommunications company)
dropped call phr. 16:09
通话中断、掉线
profit pools phr. 16:09
利润池,某行业全部可争夺的利润总量
compute /kəmˈpjuːt/ n. 16:56
算力(作名词用,AI 行业术语)
Begging the question phr. 16:56
(此处口语用法)引出问题;原义为循环论证
franchise /ˈfræntʃaɪz/ n. 16:56
品牌资产、招牌业务
fed into phr. v. 16:56
助推、印证(某种说法)
compounding /kəmˈpaʊndɪŋ/ v. 17:44
复利式增长
navigate /ˈnævɪɡeɪt/ v. 17:44
应对、穿行(复杂局面)
power law phr. 18:32
幂律,少数样本贡献绝大部分结果的分布规律
consolidated /kənˈsɑːlɪdeɪtɪd/ v. 18:32
集中、整合
dipping down into phr. v. 18:32
(从公开市场)向下延伸进入(私募)
LPs n. 19:14
有限合伙人(limited partners),基金的出资方
cohesive /koʊˈhiːsɪv/ adj. 19:14
连贯的、有凝聚力的
playbook /ˈpleɪbʊk/ n. 19:14
打法、套路手册
ledger /ˈledʒər/ n. 19:45
账本;on the positive side of the ledger 从好的一面看
counterintuitive /ˌkaʊntərɪnˈtuːɪtɪv/ adj. 19:45
反直觉的
K-shape n. 20:17
K 型分化,一部分上行一部分下行的经济格局
capital allocators phr. 20:52
资本配置者,决定资金投向的机构或个人
yolo /ˈjoʊloʊ/ v. 20:52
(俚)孤注一掷地全押(you only live once)
brittle /ˈbrɪtl/ adj. 20:52
脆弱的、易崩的
high-net-worth adj. 21:41
高净值的(个人)
pushback /ˈpʊʃbæk/ n. 22:11
反驳、异议
at scale phr. 22:11
在大规模上
equalizer /ˈiːkwəlaɪzər/ n. 23:00
拉平器,使各方处于同一标准的力量
antiseptic /ˌæntiˈseptɪk/ n. 23:00
消毒剂(比喻清除虚假的力量)
scrutiny /ˈskruːtəni/ n. 23:00
严格审视
withstand /wɪðˈstænd/ v. 23:00
经受、顶住
short sellers n. 23:00
做空者
pontificators /pɑːnˈtɪfɪkeɪtərz/ n. 23:00
夸夸其谈、好发高论的人
tactical /ˈtæktɪkl/ adj. 23:43
战术性的、具体操作层面的
disinfectant /ˌdɪsɪnˈfektənt/ n. 23:43
消毒剂
passive buying phr. 23:43
被动买入,指指数基金按规则买入而非主动判断
wash through phr. v. 23:43
消化、清洗掉(过剩供需)
compounders /kəmˈpaʊndərz/ n. 24:12
复利型公司,能持续复合增长的企业
survivor bias phr. 24:12
幸存者偏差
dented /ˈdentɪd/ v. 24:12
(此处)改变、撼动(轨迹)
trajectory /trəˈdʒektəri/ n. 24:12
轨迹、发展路径
commodities /kəˈmɑːdətiz/ n. 24:46
大宗商品,喻无差异化、只能拼价格的产品
disproven /dɪsˈpruːvn/ v. 24:46
被证伪
swelled /sweld/ v. 24:46
膨胀、扩大
plowed /plaʊd/ v. 25:21
plow money into 把大笔钱砸进
deck /dek/ n. 25:21
幻灯片、演示材料
re-anchors /riːˈæŋkərz/ v. 25:51
重新锚定
conviction /kənˈvɪkʃn/ n. 25:51
(投资)坚定信念
ground truths phr. 25:51
基本事实、可验证的底层数据
multiple of earnings phr. 25:51
盈利倍数,即市盈率
wrath /ræθ/ n. 26:43
愤怒、震怒(此处带戏谑)
ASIC /ˈeɪsɪk/ n. 26:43
专用集成电路(application-specific integrated circuit)
extrapolating /ɪkˈstræpəleɪtɪŋ/ v. 27:18
外推、由已知趋势推断
durability of earnings phr. 27:51
盈利持久性
saturation /ˌsætʃəˈreɪʃn/ n. 27:51
饱和
breakup /ˈbreɪkʌp/ n. 28:29
(反垄断)拆分
rebalanced /riːˈbælənst/ v. 28:57
(投资组合)重新平衡、调仓
bearish /ˈberɪʃ/ adj. 29:20
看空的、悲观的
influx /ˈɪnflʌks/ n. 29:20
涌入
GPs n. 29:20
普通合伙人(general partners),基金管理方
mausoleum /ˌmɔːsəˈliːəm/ n. 29:59
陵墓(此处戏称豪宅)
have no clue phr. 29:59
完全不知道
addressing /əˈdresɪŋ/ v. 29:59
(商业)面向、切入(某市场)
price war n. 30:47
价格战
pull a price lever phr. 30:47
动用价格杠杆,即降价竞争
lock it in phr. 31:20
敲定、说定
grounding /ˈɡraʊndɪŋ/ adj. 31:53
让人脚踏实地的、让人安定的
meditate on phr. v. 31:53
静心思考、沉思
精读便签
下载便签 手机:长按图片也可保存
← 上一期 · NO.206Satya Nadella on the AI Doomer Slowdown, Microsoft’s Master Plan & Who Wins AI 下一期 · NO.208 →How Chamath Optimized His Health
苏菲周报 · THE WEEKLY 每周一封,
追问一个大问题。
苏菲拉底的每周来信,写这一周在追问的问题和看到的回应。
苏菲拉底
ASK THE BIG QUESTIONS · THINK DEEPLY · SEE THE WORLD DIFFERENTLY
苏菲拉底微信公众号二维码 微信公众号
© 2026 苏菲拉底 · 内容仅供学习 [email protected]